
Deferred Tax Explained Under IAS 12 and UAE Corporate Tax – Complete Guide
Learn Deferred Tax under IAS 12 and UAE Corporate Tax with simple examples. Understand Deferred Tax Liability, Deferred Tax Asset, Temporary Differences, Tax Losses, and calculation methods with practical explanations.

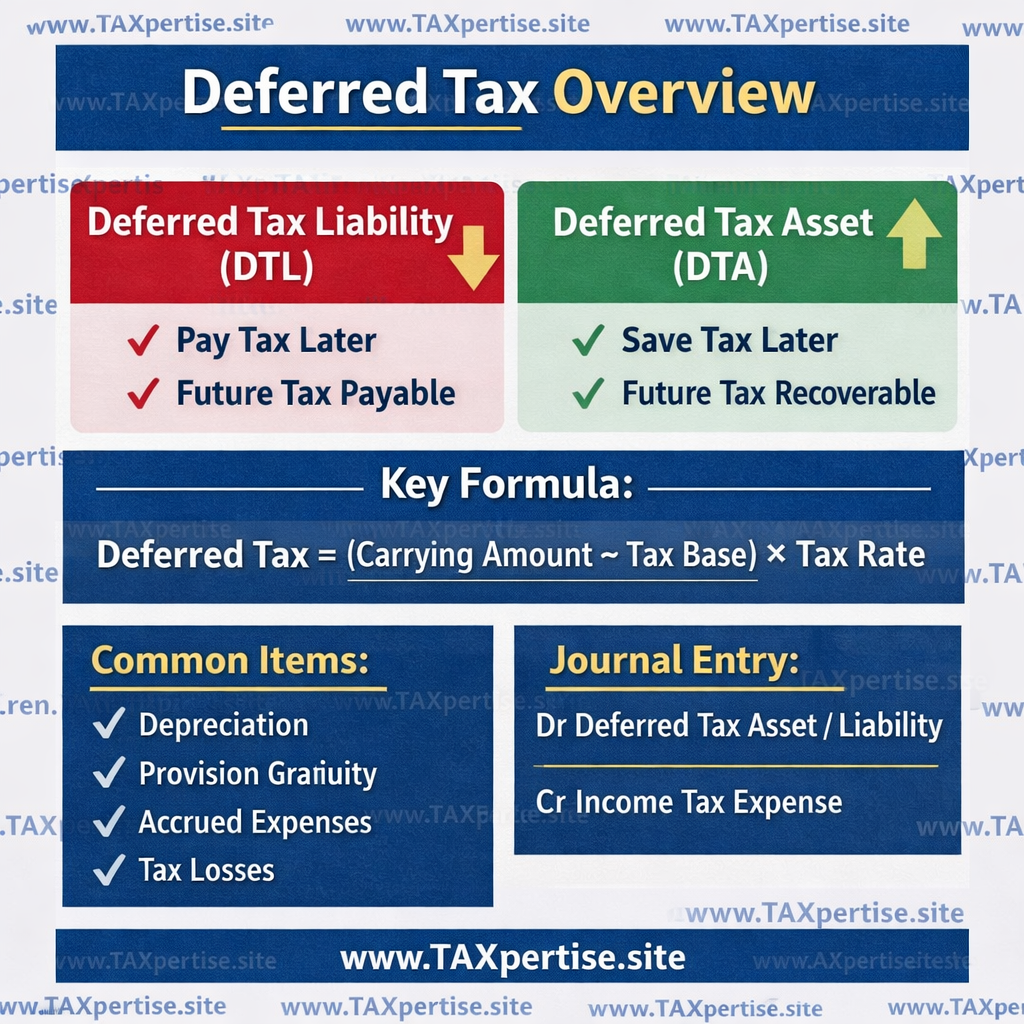
Deferred Tax Explained Under IAS 12 and UAE Corporate Tax
Deferred Tax is one of the most important concepts in Financial Reporting (IFRS) and UAE Corporate Tax. Many finance professionals confuse Deferred Tax because it involves both accounting rules and tax law. This guide explains Deferred Tax in a simple and practical way.
1. What is Deferred Tax?
Deferred Tax is the tax that will be paid or saved in the future due to temporary differences between accounting profit and taxable profit.
Simple definition:
Deferred Tax = Tax impact of temporary differences between Carrying Amount and Tax Base.
2. Why Deferred Tax Arises?
Deferred tax arises because:
- Accounting rules (IFRS) are different from Tax Law
- Some expenses are allowed in accounting but not in tax
- Some depreciation rates are different
- Some income is taxed earlier or later
3. Deferred Tax Liability vs Deferred Tax Asset
| Type | Meaning |
|---|---|
| Deferred Tax Liability (DTL) | Tax payable in future |
| Deferred Tax Asset (DTA) | Tax recoverable in future |
Golden Rule:
- Save tax today → Deferred Tax Liability
- Pay extra tax today → Deferred Tax Asset
4. Carrying Amount vs Tax Base
| Term | Meaning |
|---|---|
| Carrying Amount | Value of asset/liability in accounting books |
| Tax Base | Value of asset/liability as per tax law |
Deferred Tax Formula
Deferred Tax = (Carrying Amount – Tax Base) × Tax Rate
5. Temporary vs Permanent Difference
| Difference Type | Deferred Tax |
|---|---|
| Temporary Difference | Yes |
| Permanent Difference | No |
Temporary Differences Examples
- Depreciation difference
- Provision for gratuity
- Leave salary provision
- Accrued expenses
- IFRS 16 Lease
Permanent Differences Examples
- Fines and penalties
- 50% entertainment expenses disallowed
- Non-allowed donations
- Exempt dividend income
6. Depreciation Example (Deferred Tax Liability)
| Particular | Accounting | Tax |
|---|---|---|
| Depreciation | 10,000 | 30,000 |
Carrying Amount = 90,000
Tax Base = 70,000
Temporary Difference = 20,000
Deferred Tax Liability = 20,000 × 9% = 1,800
7. Deferred Tax Asset Example (Provision)
If provision expense is allowed in accounting but not allowed in tax until paid, it creates Deferred Tax Asset because company pays more tax now and will save tax later.
8. Deferred Tax on Tax Losses
If a company has tax losses, it can carry forward losses and reduce future taxable income.
Deferred Tax Asset = Tax Loss × Tax Rate
9. IAS 12 Method – Balance Sheet Approach
As per IAS 12, deferred tax is calculated using the Balance Sheet Method:
- Take Carrying Amount
- Calculate Tax Base
- Find Temporary Difference
- Apply Tax Rate
- Identify DTL or DTA
10. Presentation in Financial Statements
| Statement | Treatment |
|---|---|
| Balance Sheet | Show as Asset or Liability |
| Profit & Loss | Shown as Deferred Tax Expense |
11. Deferred Tax in UAE Corporate Tax
Deferred tax is an IFRS concept and used in financial statements. It is not directly payable to FTA but affects financial reporting and tax planning under UAE Corporate Tax.
For more details on UAE Corporate Tax, visit the official FTA website:
Federal Tax Authority – UAE
12. Deferred Tax Journal Entries
Deferred tax is recorded through journal entries at the end of the financial year.
When Deferred Tax Liability (DTL) arises
Situation: Company saves tax today and will pay more tax in future.
Dr Income Tax Expense
    Cr Deferred Tax Liability
When Deferred Tax Asset (DTA) arises
Situation: Company pays more tax today and will save tax in future.
Dr Deferred Tax Asset
    Cr Income Tax Expense
13. Deferred Tax Settlement / Reversal
Deferred tax does not remain forever. It reverses in future when the temporary difference reverses.
Example: Depreciation difference
| Year | Accounting Dep | Tax Dep | Difference |
|---|---|---|---|
| Year 1 | 10,000 | 30,000 | 20,000 |
| Year 2 | 10,000 | 21,000 | 11,000 |
| Year 3 | 10,000 | 14,700 | 4,700 |
| Later Years | 10,000 | Less | Reversal |
In later years, tax depreciation becomes lower than accounting depreciation, so the earlier Deferred Tax Liability starts reversing.
Journal Entry for Reversal (DTL)
Dr Deferred Tax Liability
    Cr Income Tax Expense
This reduces tax expense in future.
14. Full Deferred Tax Example (Complete Calculation)
| Item | Carrying Amount | Tax Base | Difference | Tax 9% | DTL/DTA |
|---|---|---|---|---|---|
| Fixed Assets | 90,000 | 70,000 | 20,000 | 1,800 | DTL |
| Provision Gratuity | 10,000 | 0 | 10,000 | 900 | DTA |
| Accrued Expense | 5,000 | 0 | 5,000 | 450 | DTA |
Total DTL = 1,800
Total DTA = 1,350
Net Deferred Tax Liability = 450
Journal Entry:
Dr Income Tax Expense 450
    Cr Deferred Tax Liability 450
15. Deferred Tax in Financial Statements
Balance Sheet
- Deferred Tax Asset → Non-current Asset
- Deferred Tax Liability → Non-current Liability
Profit & Loss
Total Tax Expense is calculated as:
Current Tax
+ Deferred Tax
= Total Tax Expense
16. Current Tax vs Deferred Tax
| Type | Meaning |
|---|---|
| Current Tax | Tax payable to FTA now |
| Deferred Tax | Tax payable or recoverable in future |
17. Common Items Creating Deferred Tax
| Item | Deferred Tax Type |
|---|---|
| Depreciation | DTL |
| Provision for Gratuity | DTA |
| Leave Salary Provision | DTA |
| Accrued Expenses | DTA |
| Revaluation Gain | DTL |
| Tax Losses | DTA |
18. Golden Rules of Deferred Tax
- If you save tax today → Deferred Tax Liability
- If you pay extra tax today → Deferred Tax Asset
19. Complete Deferred Tax Calculation Process
- Find Carrying Amount
- Find Tax Base
- Calculate Temporary Difference
- Apply Tax Rate
- Identify DTL or DTA
- Pass Journal Entry
- Show in Financial Statements
20. IAS 12 Official Definition
Deferred tax is the tax payable or recoverable in future periods arising from temporary differences between the carrying amount of assets and liabilities in the statement of financial position and their tax base.
Conclusion
Deferred Tax arises due to temporary differences between accounting and tax treatment. Understanding Carrying Amount vs Tax Base is the key to calculating deferred tax correctly under IAS 12 and UAE Corporate Tax.
What's Your Reaction?
 Like
1
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)