
UAE Corporate Tax Treatment of Depreciation – Complete Guide
Learn the UAE Corporate Tax treatment of depreciation, including capital assets, add-backs, disallowed depreciation, and practical examples. Complete guide for UAE CT computation.


UAE Corporate Tax Treatment of Depreciation – Complete Guide
Introduction
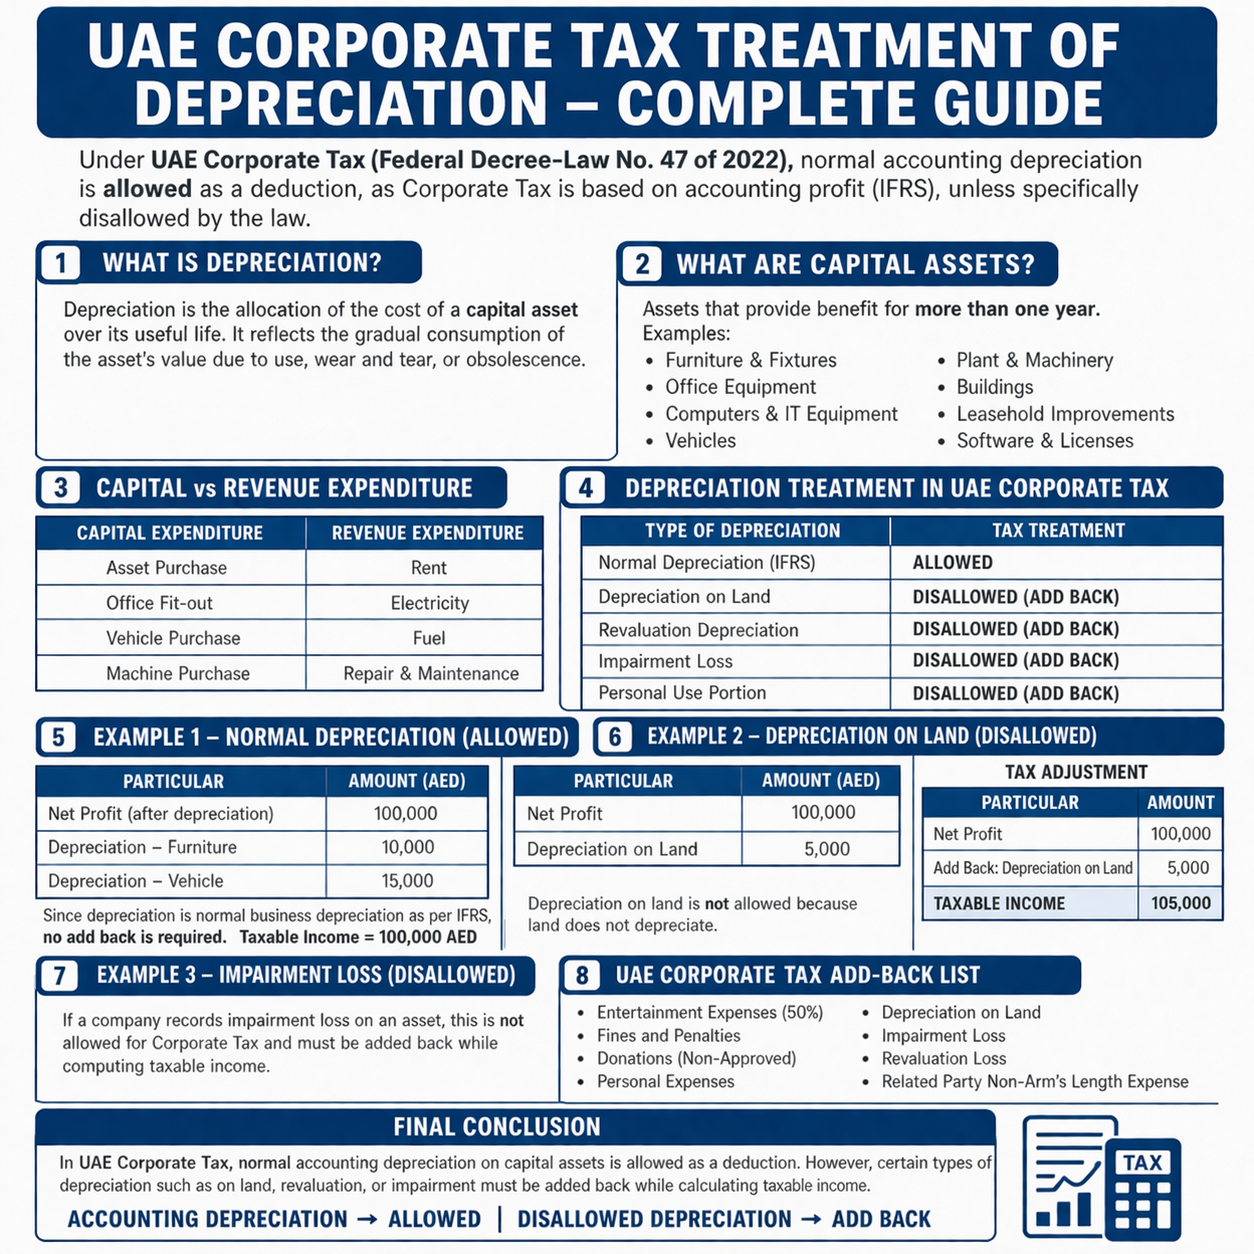
Under UAE Corporate Tax (Federal Decree-Law No. 47 of 2022), the treatment of depreciation is different from many other countries. In the UAE, Corporate Tax is based on accounting profit as per IFRS, therefore normal accounting depreciation is generally allowed as a deduction, unless specifically disallowed by the Corporate Tax Law.
What is Depreciation in Corporate Tax?
Depreciation is the allocation of the cost of a capital asset over its useful life. Since capital assets provide benefit for more than one year, they are not treated as expenses immediately; instead, they are depreciated over time.
What are Capital Assets?
Capital assets are assets that provide benefit for more than one year. Common examples include:
- Furniture and fixtures
- Office equipment
- Computers and IT equipment
- Vehicles
- Plant and machinery
- Buildings
- Leasehold improvements (office fit-out)
- Software and licenses
Capital Expenditure vs Revenue Expenditure
| Capital Expenditure | Revenue Expenditure |
|---|---|
| Asset purchase | Rent |
| Office fit-out | Electricity |
| Vehicle purchase | Fuel |
| Machine purchase | Repair & maintenance |
Depreciation Treatment in UAE Corporate Tax
| Type of Depreciation | Corporate Tax Treatment |
|---|---|
| Normal depreciation (IFRS) | Allowed |
| Depreciation on land | Disallowed (Add back) |
| Revaluation depreciation | Disallowed (Add back) |
| Impairment loss | Disallowed (Add back) |
| Personal use portion | Disallowed (Add back) |
Example 1 – Normal Depreciation (Allowed)
A company has the following profit and loss account:
| Particular | Amount (AED) |
|---|---|
| Net Profit (after depreciation) | 100,000 |
| Depreciation – Furniture | 10,000 |
| Depreciation – Vehicle | 15,000 |
Since depreciation is normal business depreciation as per IFRS, no add back is required.
Taxable Income = 100,000 AED
Example 2 – Depreciation on Land (Disallowed)
| Particular | Amount (AED) |
|---|---|
| Net Profit | 100,000 |
| Depreciation on Land | 5,000 |
Depreciation on land is not allowed because land does not depreciate.
Tax Adjustment:
| Particular | Amount |
|---|---|
| Net Profit | 100,000 |
| Add back depreciation on land | 5,000 |
| Taxable Income | 105,000 |
Example 3 – Impairment Loss (Disallowed)
If a company records impairment loss on an asset, this is not allowed for Corporate Tax and must be added back.
UAE Corporate Tax Add-Back List
| Expense | Add Back |
|---|---|
| Entertainment expenses (50%) | Yes |
| Fines and penalties | Yes |
| Donations (non-approved) | Yes |
| Personal expenses | Yes |
| Depreciation on land | Yes |
| Impairment loss | Yes |
| Revaluation loss | Yes |
| Normal depreciation | No |
Final Conclusion
In UAE Corporate Tax, normal depreciation charged in the profit and loss account is allowed as a deduction because Corporate Tax is based on accounting profit. However, certain types of depreciation such as depreciation on land, impairment, and revaluation depreciation must be added back while calculating taxable income.
Therefore, the correct rule is:
Accounting Depreciation → Allowed
Disallowed Depreciation → Add Back
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)