
UAE VAT Article 51 – Designated Zones Explained (Goods Only)
Complete explanation of UAE VAT Article 51 for Designated Zones, including conditions, VAT treatment of goods, imports, exports, and consumption rules with practical examples.

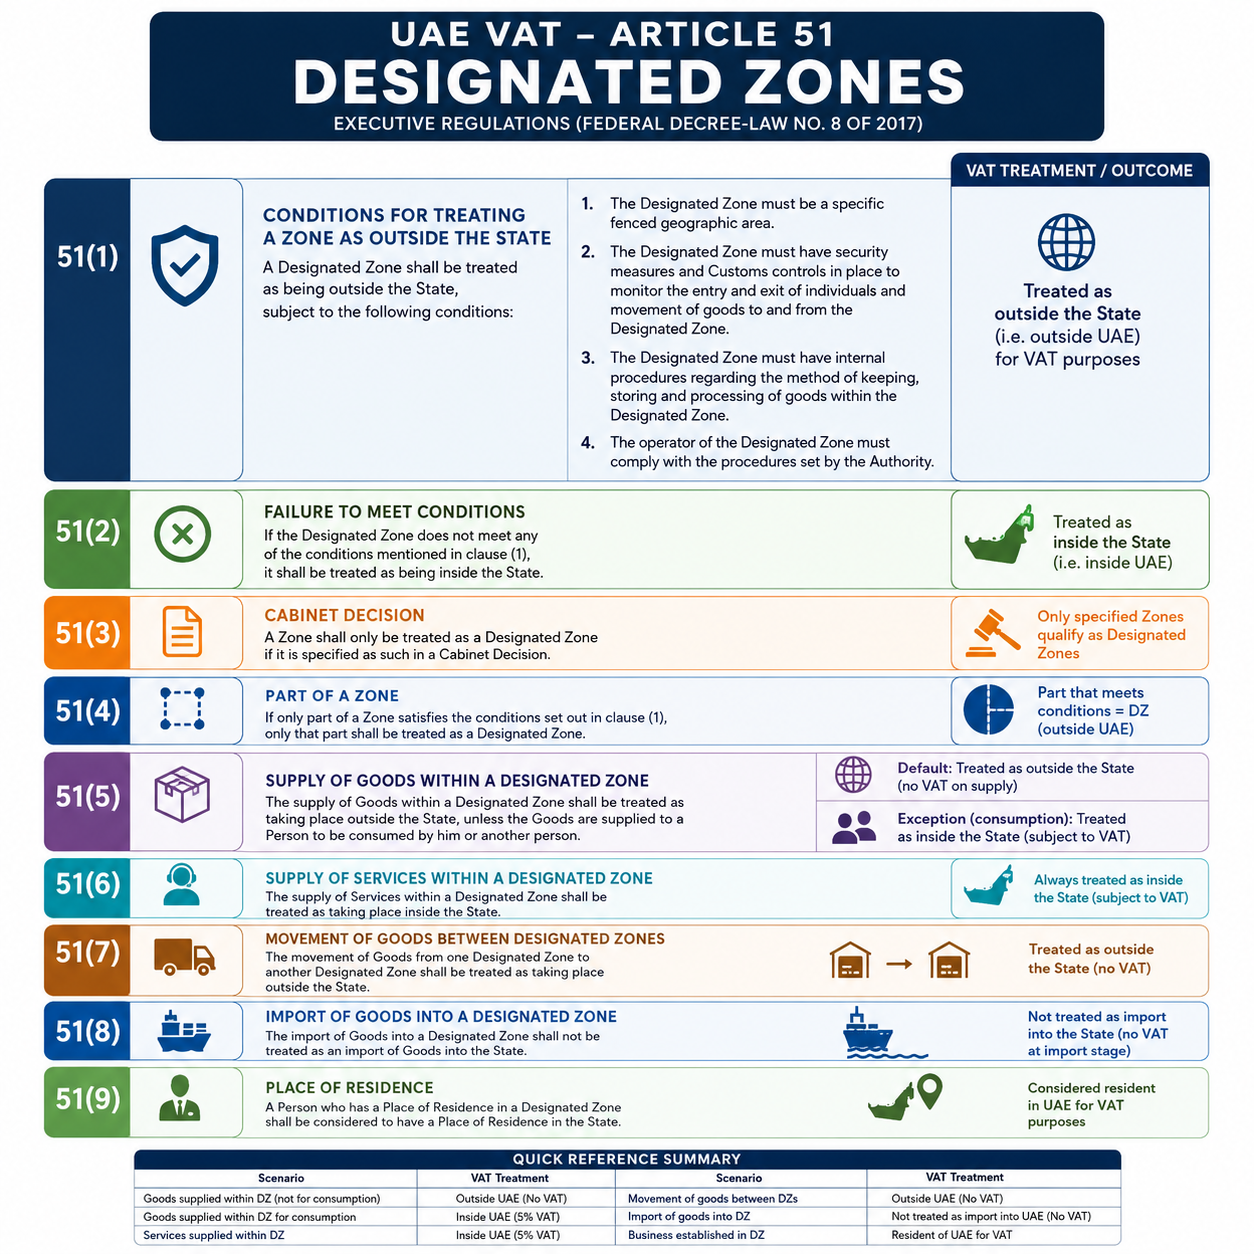
UAE VAT Article 51 – Designated Zones (Full Legal Structure)
Article 51 of the UAE VAT Executive Regulations provides the full legal framework for Designated Zones. This article defines when a zone is treated as outside the UAE and how VAT applies to goods and services within such zones.
1. Clause 51(1) – Conditions to Qualify as Designated Zone
- Specific fenced geographic area
- Security measures and customs controls
- Internal procedures for storing, processing and tracking goods
- Operator complies with FTA procedures
2. Clause 51(2) – Failure of Conditions
If any condition is not met, the Designated Zone is treated as being inside the UAE for VAT purposes.
3. Clause 51(3) – Cabinet Designation
Only Free Zones specified by a Cabinet Decision qualify as Designated Zones.
4. Clause 51(4) – Partial Qualification
If only part of a zone meets the required conditions, only that part is treated as a Designated Zone.
5. Clause 51(5) – Supply of Goods (Core Rule)
Supply of goods within a Designated Zone is treated as taking place outside the UAE.
Exception: If goods are supplied to be consumed, the supply is treated as taking place inside the UAE and subject to 5% VAT.
Meaning of Consumption
Consumption includes use, utilisation, or application of goods rather than resale or incorporation into other goods.
6. Clause 51(6) – Supply of Services
All services supplied in a Designated Zone are treated as supplied within the UAE and are subject to normal VAT rules.
7. Clause 51(7) – Transfer Between Designated Zones
Transfer of goods between Designated Zones is not subject to VAT.
8. Clause 51(8) – Import into Designated Zone
Goods entering a Designated Zone are not treated as imports into the UAE and therefore no VAT is due at this stage.
9. Clause 51(9) – Place of Residence
Businesses operating in Designated Zones are considered residents in the UAE for VAT purposes and must comply with VAT registration, filing, and reporting obligations.
10. Consolidated VAT Treatment of Goods
| Scenario | VAT Treatment |
|---|---|
| Goods traded within DZ | Outside UAE |
| Goods consumed | 5% VAT |
| Goods transferred between DZs | No VAT |
| Goods entering DZ | No import VAT |
| Services in DZ | 5% VAT |
Conclusion
Article 51 establishes a conditional offshore VAT regime for goods while keeping services and businesses fully within the UAE VAT system. The classification depends on whether the zone meets legal conditions and whether goods are consumed or traded.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)