
UAE VAT on Used Cars & Asset Sales | Profit Margin Scheme Explained
Learn how the UAE VAT Profit Margin Scheme (PMS) applies to used cars, second-hand goods, and asset sales, with examples and FTA rules.

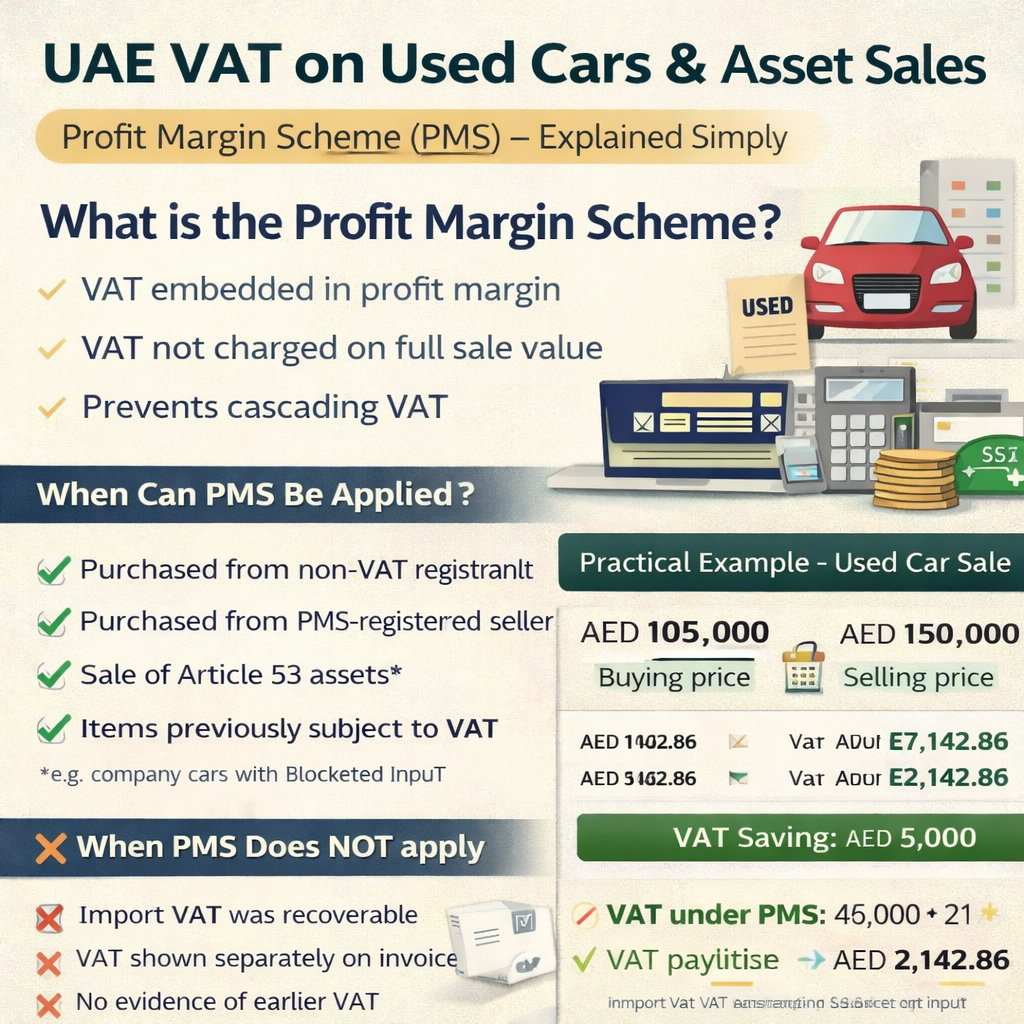
🟢 UAE VAT on Used Cars & Asset Sales
Profit Margin Scheme (PMS) – Explained Simply
If your business sells used cars, second-hand goods, or company assets, you may be paying excess VAT without realising it.
The UAE VAT Profit Margin Scheme (PMS) allows VAT to be calculated only on the profit margin, instead of the full selling price — but only if strict FTA conditions are met.
🔹 What Is the Profit Margin Scheme?
Under the Profit Margin Scheme:
-
VAT is embedded in the profit margin
-
VAT is not charged on the full selling price
-
This prevents VAT cascading where input VAT was not recoverable
PMS is especially relevant for used-car dealers, asset disposals, and businesses selling blocked-VAT assets.
🔹 When Can PMS Be Applied?
PMS may be applied if any one of the following conditions is met:
✅ Goods purchased from a non-VAT registrant (e.g. private individual)
✅ Goods purchased from a VAT registrant who also applied PMS
✅ Sale of Article 53 assets (input VAT blocked – e.g. company cars used privately)
✅ Goods were previously subject to VAT (post-2018)
❌ When PMS Does NOT Apply
PMS is not allowed in the following cases:
❌ Imported goods where import VAT was recoverable
❌ VAT is shown separately on the sales invoice
❌ No evidence exists that VAT was previously incurred
🔹 Practical Example – Used Car Sale
Purchase price (incl. costs): AED 105,000
Selling price: AED 150,000
Profit Margin: AED 45,000
VAT under PMS
45,000 ÷ 21 = AED 2,142.86
VAT under Normal VAT
150,000 × 5 / 105 = AED 7,142.86
👉 VAT saving: AED 5,000 on a single transaction
🔹 Article 53 Asset Example – Company Car
Purchase: AED 500,000
Input VAT: AED 25,000 (blocked)
Selling price: AED 530,000
Profit Margin: AED 5,000
VAT payable under PMS: AED 238.10
✔ PMS is allowed even though the asset is a fixed asset, not trading stock.
🔹 Sold at a Loss?
If the asset is sold at cost or at a loss:
➡️ No VAT is payable under PMS
⚠️ Losses cannot be offset against profitable PMS sales
🔹 Critical Invoicing Rules (High FTA Focus)
✔ Invoice must clearly state:
“VAT charged under the Profit Margin Scheme”
❌ VAT amount must NOT be shown separately
❌ Showing VAT separately = PMS automatically disallowed
🔹 VAT Return Reporting (UAE VAT Return)
-
Box 1: Selling value (net of VAT on margin) + VAT on margin
-
Box 9: Purchase price only (no VAT amount)
📚 Legal References
-
UAE VAT Executive Regulation – Article 29 (Profit Margin Scheme)
-
Article 53 – Blocked Input VAT
-
FTA VAT Guide: Profit Margin Scheme (VATGPM1) – January 2026
✅ Key Takeaway
The Profit Margin Scheme is one of the most powerful VAT cost-saving tools in the UAE for used-car dealers and asset disposals — but documentation, eligibility, and invoicing errors can completely invalidate it.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)