
UAE VAT Administrative Exceptions Explained | FTA Guide VATGEX1
FTA’s VAT Administrative Exceptions Guide (VATGEX1 – Dec 2025) explains procedural VAT relief, eligibility, timelines, and limitations for UAE businesses.

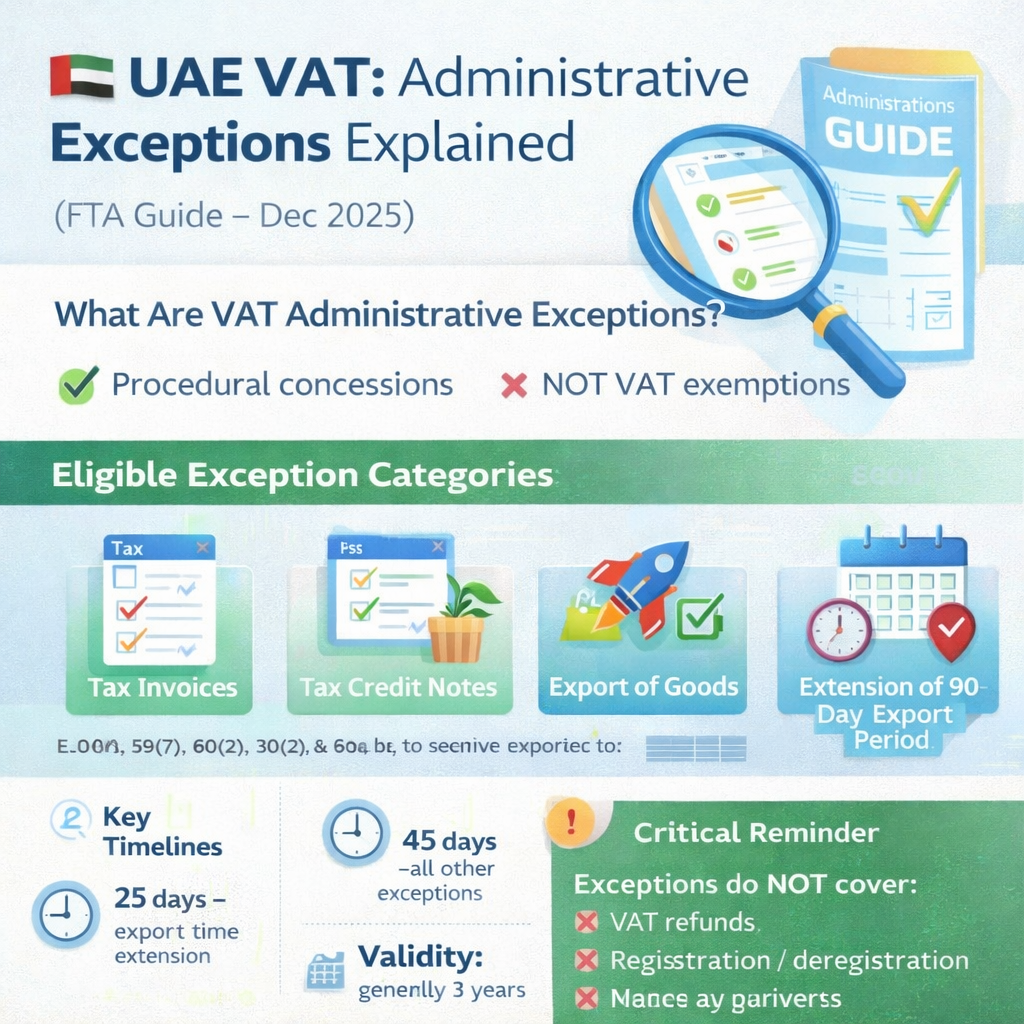
🟢 UAE VAT – Administrative Exceptions Explained
(FTA Guide VATGEX1 – December 2025)
The UAE Federal Tax Authority (FTA) has issued the updated VAT Administrative Exceptions Guide (VATGEX1 – December 2025), clarifying circumstances where VAT-registered businesses may receive limited procedural relief — without compromising VAT compliance.
These concessions are strictly controlled and subject to strong audit documentation.
🔹 What Are VAT Administrative Exceptions?
VAT administrative exceptions are:
-
✔ Procedural concessions
-
❌ Not VAT exemptions
-
❌ Not tax reliefs
They apply only in specific situations where full compliance is impractical, provided sufficient records are maintained and FTA approval is obtained.
🔹 Eligible VAT Administrative Exception Categories
FTA may grant exceptions in the following areas:
🔸 Tax Invoices
-
Relief from certain invoice details
-
Alternative issuance methods in justified cases
🔸 Tax Credit Notes
-
Simplified issuance
-
Non-issuance in limited, approved circumstances
🔸 Export of Goods
-
Acceptance of alternative export evidence
-
Applicable where standard documentation is unavailable
🔸 Extension of the 90-Day Export Period
-
Additional time granted where justified and supported
📚 Legal References (Executive Regulation):
-
Article 59(7)
-
Article 60(2)
-
Article 30(6)
-
Article 30(7)
🔹 Who Can Apply for Administrative Exceptions?
Only VAT-registered persons (TRN holders) may apply via EmaraTax.
Applications can be submitted by:
-
✔ Authorised signatory
-
✔ Registered Indirect Tax Agent
-
✔ Representative Member (for VAT Tax Groups)
🔹 Key FTA Timelines
⏱ 25 business days
→ Export time-extension requests
⏱ 45 business days
→ All other administrative exception requests
📆 Validity Period
-
Generally up to 3 years
-
Earlier effective date of up to 5 years, if approved by FTA
⚠️ Critical Limitations (Very Important)
Administrative exceptions DO NOT apply to:
❌ VAT refunds
❌ VAT registration or deregistration
❌ Waiver or reduction of penalties
❌ Technical VAT interpretations or rulings
🔹 Important E-Invoicing Impact
📌 Invoice-related administrative exceptions will automatically expire once UAE e-Invoicing becomes mandatory.
Businesses relying on invoice concessions must prepare for full digital compliance.
✅ Key Takeaway
VAT administrative exceptions are a compliance support mechanism, not a workaround.
Approval depends on clear justification, strong documentation, and audit-ready records.
Misuse or weak evidence may result in rejection, assessments, or penalties.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)