
UAE IFRS Year End Closing Entries
Learn the complete list of IFRS-compliant year-end closing entries for UAE businesses. Covers accruals, revenue recognition, depreciation, provisions, ECL, inventory, tax, and final closing entries under IFRS.

IFRS Year-End Closing Entries: A Complete Guide for UAE Businesses
Year-end closing entries under IFRS are a critical part of financial reporting for businesses operating in the UAE. These entries ensure that financial statements present a true and fair view in line with the accrual basis of accounting and International Financial Reporting Standards.
This guide explains all major IFRS year-end closing entries, with practical explanations relevant to UAE companies, including those subject to Corporate Tax and VAT.
Why Year-End Closing Entries Are Important Under IFRS
IFRS requires entities to recognize income and expenses in the period to which they relate, regardless of cash movements. Incorrect or missing closing entries can lead to:
- Misstated profits
- Audit qualifications
- Corporate Tax and compliance risks in the UAE
1. Revenue Recognition Adjustments (IFRS 15)
Accrued Revenue (Earned but Not Invoiced)
When goods or services are delivered before year-end but the invoice is issued later:
Journal Entry:
Dr Accrued Revenue
Cr Revenue
Deferred Revenue (Invoiced but Not Earned)
Advance receipts where performance obligations are not yet satisfied:
Journal Entry:
Dr Revenue
Cr Deferred Revenue
2. Expense Accruals (Accrual Principle)
Expenses incurred during the year but not yet invoiced or paid must be recognized.
Examples: Audit fees, utilities, legal fees, salaries
Journal Entry:
Dr Expense
Cr Accrued Expenses
3. Prepaid Expense Adjustments
Payments made in advance for future periods must be carried forward as assets.
Examples: Insurance, rent, software licenses
Journal Entry:
Dr Prepaid Expense
Cr Expense
4. Depreciation and Amortisation (IAS 16 & IAS 38)
Depreciation of Property, Plant & Equipment
Journal Entry:
Dr Depreciation Expense
Cr Accumulated Depreciation
Amortisation of Intangible Assets
Journal Entry:
Dr Amortisation Expense
Cr Accumulated Amortisation
5. Provisions and Liabilities (IAS 37)
Provisions are recognized when there is a present obligation, it is probable, and the amount can be reliably estimated.
Examples: Legal claims, employee benefits, penalties
Journal Entry:
Dr Expense
Cr Provision
6. Expected Credit Loss – ECL (IFRS 9)
Under IFRS 9, businesses must recognize expected credit losses even if no default has occurred.
Journal Entry:
Dr Impairment Loss
Cr Allowance for Doubtful Debts
7. Inventory Adjustments (IAS 2)
Inventory at Lower of Cost or NRV
If net realizable value is lower than cost:
Journal Entry:
Dr Inventory Write-down Expense
Cr Inventory
8. Foreign Currency Revaluation (IAS 21)
Monetary assets and liabilities in foreign currency must be revalued at the closing rate.
Journal Entry (Loss):
Dr Exchange Loss
Cr Liability / Asset
9. Income Tax Adjustments (IAS 12)
Current Tax Provision
Journal Entry:
Dr Income Tax Expense
Cr Income Tax Payable
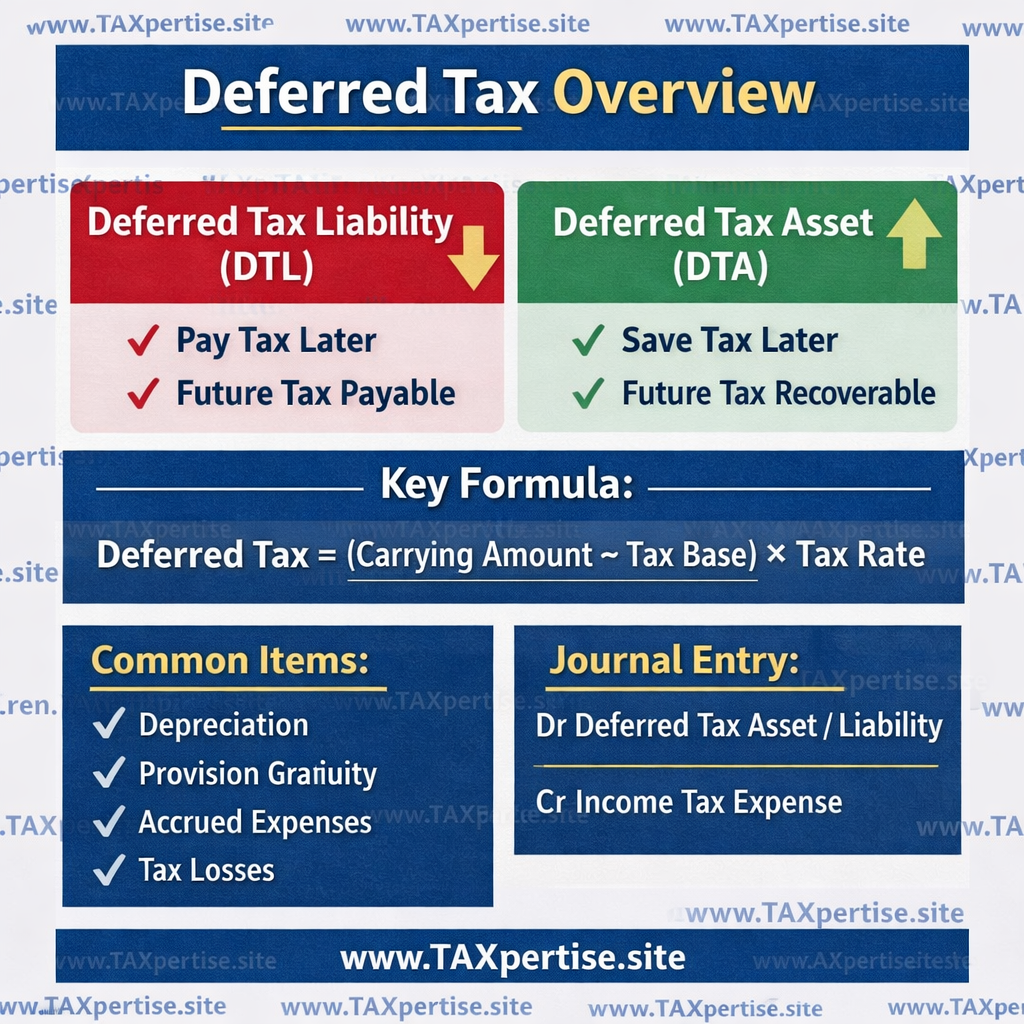
Deferred Tax (Where Applicable)
Journal Entry:
Dr / Cr Deferred Tax Asset or Liability
Cr / Dr Tax Expense
10. Final Closing Entries
Transfer Profit or Loss
Journal Entry:
Dr Revenue
Cr Profit & Loss
Journal Entry:
Dr Profit & Loss
Cr Expenses
Transfer Net Profit to Retained Earnings
Journal Entry:
Dr Profit & Loss
Cr Retained Earnings
IFRS Compliance in the UAE
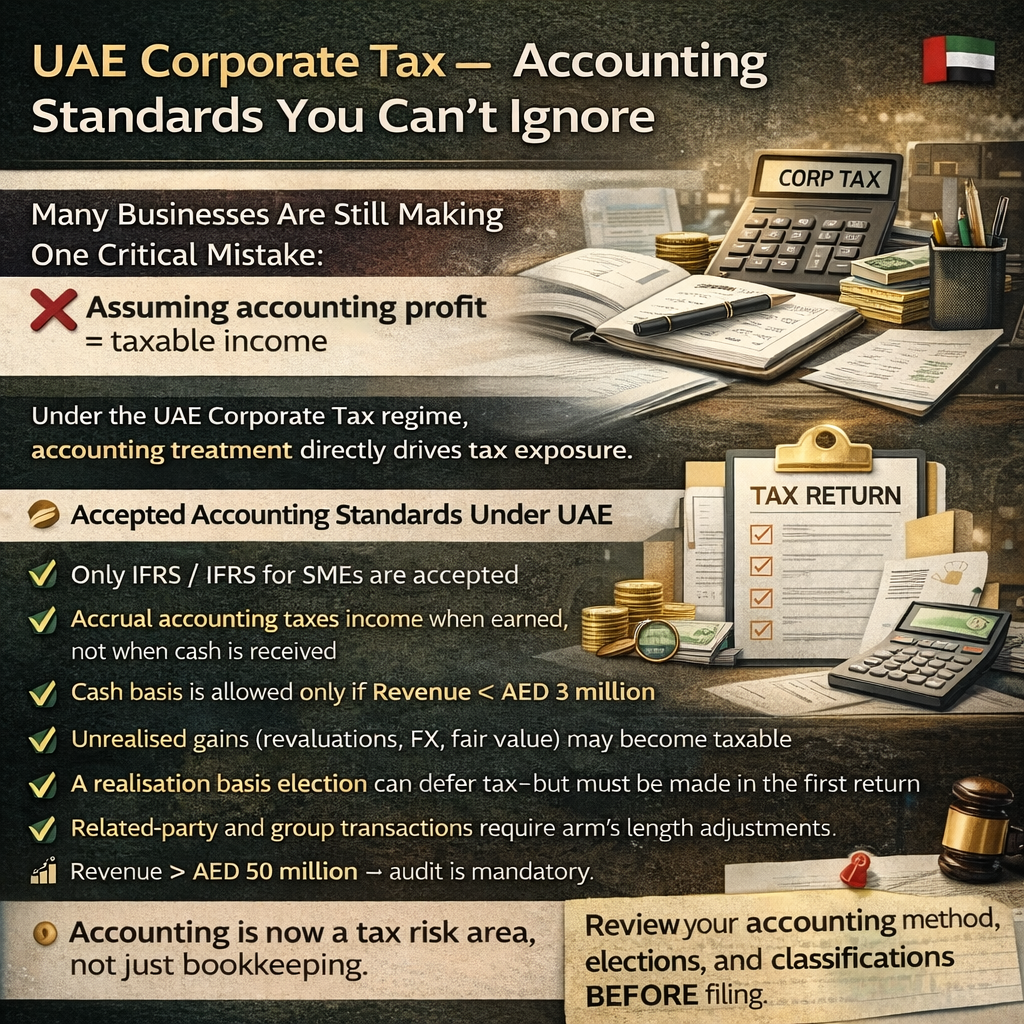
All UAE entities preparing financial statements are required to follow IFRS. Official standards and interpretations can be accessed from the IFRS Foundation:
Official IFRS Website – IFRS Foundation
Conclusion
Accurate IFRS year-end closing entries are essential for audit readiness, Corporate Tax compliance, and reliable financial reporting in the UAE. A structured closing process reduces financial risk and ensures compliance with international standards.
If you need assistance with IFRS closing entries, UAE Corporate Tax alignment, or system implementation, professional review is always recommended.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)