
Unrealized Gains in UAE Corporate Tax: Full Technical Guide with Complete Tax Computation (2026)
Detailed UAE Corporate Tax guide on unrealized gains including full tax computation, add-backs, exempt income, realization vs accrual basis, and FTA compliance.

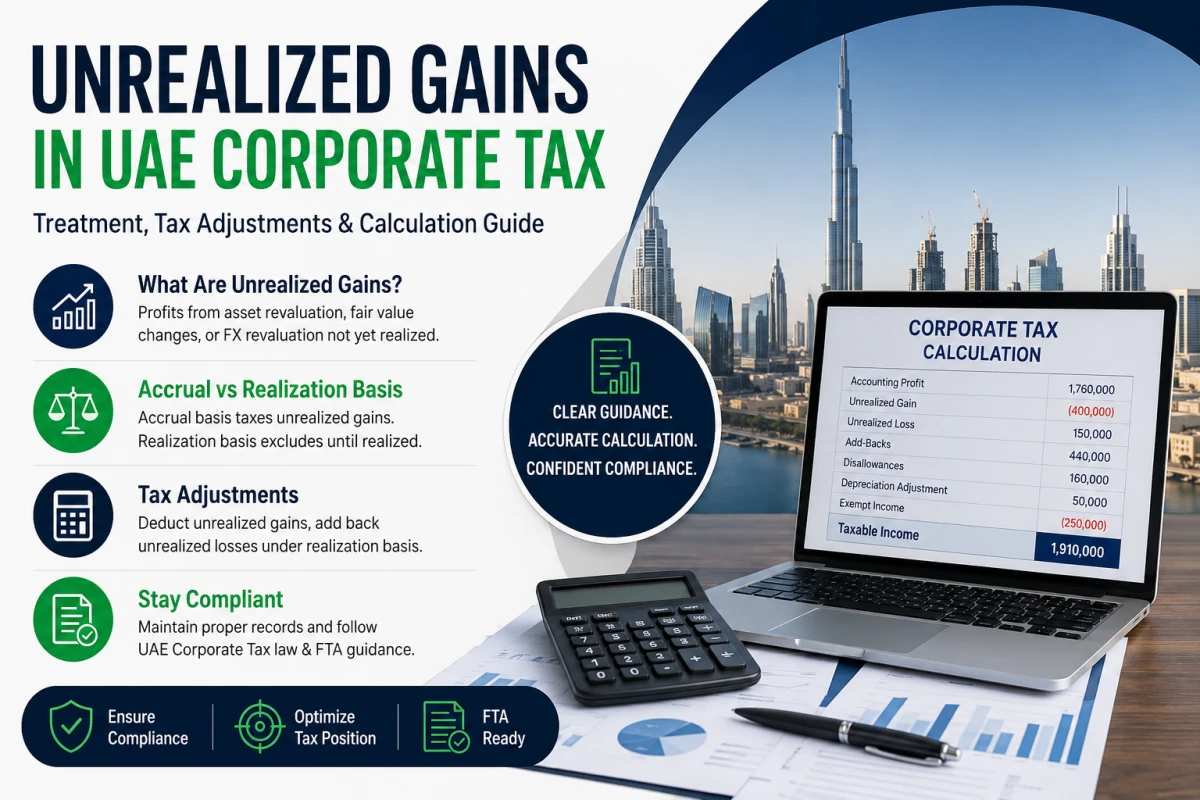
Unrealized Gains in UAE Corporate Tax: Full Technical Guide with Calculation (2026)
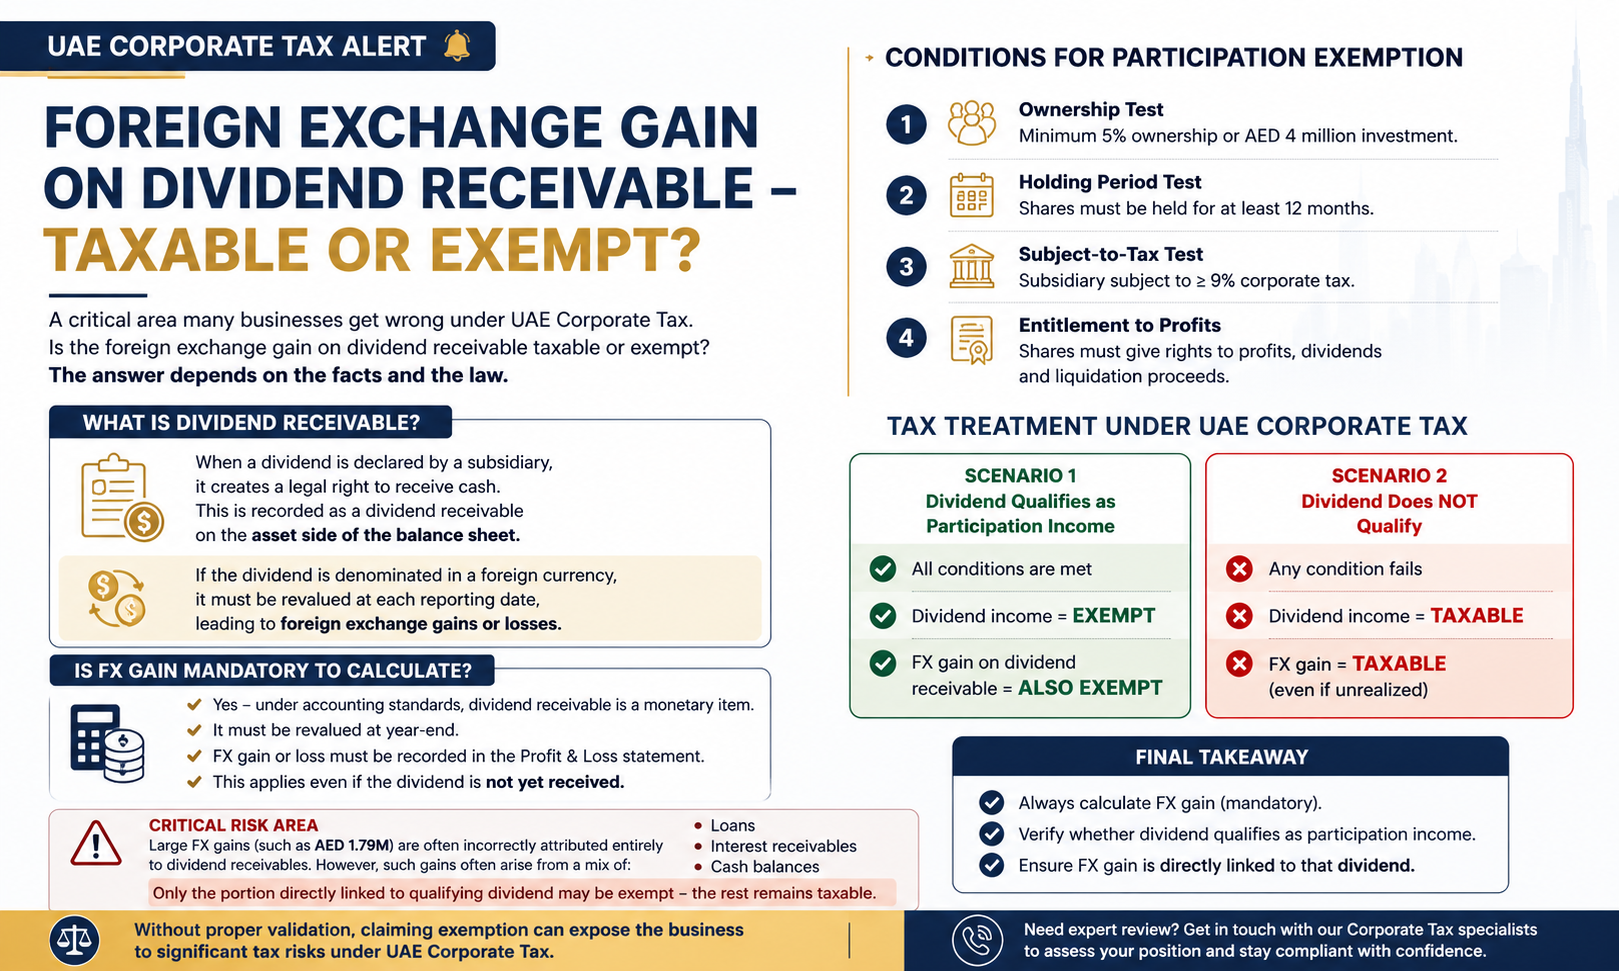
Unrealized gains refer to accounting income arising from revaluation of assets or liabilities (fair value adjustments, foreign exchange gains, financial instruments) that have not yet been realized through an actual transaction.
Legal Framework
- Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses
- IFRS Standards (IAS 40, IFRS 9, IAS 21)
- Federal Tax Authority (FTA) guidance
Taxable Income = Accounting Profit ± Tax Adjustments
Accrual vs Realization Basis
Accrual Basis (Default)
- Unrealized gains are taxable
- Unrealized losses are deductible
Realization Basis (Election)
- Unrealized gains are excluded from taxable income
- Unrealized losses are not deductible
Comprehensive UAE Corporate Tax Calculation
Scenario (Realization Basis)
| Particular | AED |
|---|---|
| Net Profit (Accounting) | 1,760,000 |
| Includes Unrealized Gain | 400,000 |
| Includes Unrealized Loss | (150,000) |
Step 1: Unrealized Adjustment
| Type | Treatment | AED |
|---|---|---|
| Unrealized Gain | Deduct | (400,000) |
| Unrealized Loss | Add Back | 150,000 |
| Net | (250,000) |
Step 2: Add-Backs
| Item | AED |
|---|---|
| Fines | 40,000 |
| Owner Expense | 80,000 |
| Provision | 100,000 |
| TP Adjustment | 150,000 |
| Interest Limitation | 70,000 |
| Total | 440,000 |
Step 3: Partial Disallowance
| Item | AED |
|---|---|
| Entertainment (50%) | 100,000 |
| Travel (50%) | 60,000 |
| Total | 160,000 |
Step 4: Depreciation
| Item | AED |
|---|---|
| Accounting Depreciation | 300,000 |
| Tax Depreciation | (250,000) |
| Net | 50,000 |
Step 5: Exempt Income
| Item | AED |
|---|---|
| Dividend Income | (250,000) |
Final Taxable Income
| Step | AED |
|---|---|
| Net Profit | 1,760,000 |
| Adjustments | 150,000 |
| Taxable Income | 1,910,000 |
Corporate Tax Liability
| Slab | AED |
|---|---|
| 0% up to 375,000 | 0 |
| 9% thereafter | 138,150 |
Treatment Upon Realization
When the asset is sold or settled:
Previously excluded gains become taxable
Only the net realized gain is taxed
Example:
Unrealized gain excluded earlier: 300,000
Final realized gain: 350,000
Taxable amount = 50,000
Common Sources of Unrealized Gains
- Investment property measured at fair value
- Foreign exchange revaluation
- Financial instruments at fair value
- Derivative contracts
Key Compliance Requirements
Businesses must maintain:
- Unrealized gain and loss tracking schedule
- Reconciliation between accounting profit and taxable income
- Supporting documentation for valuations
- Consistent application of selected tax basis
Key Adjustment Categories in UAE Corporate Tax
Add-Back Items
- Non-business expenses
- Fines and penalties
- Owner-related expenses
- Excess interest
- Transfer pricing adjustments
- General provisions
- Deductible Items
- Tax depreciation
- Allowable business expenses
- Realized losses
- Exempt Income
- Dividends (qualifying)
- Capital gains (participation exemption)
- Timing Differences
- Unrealized gains and losses
- Provisions vs actual expenses
- Accruals and prepayments
- Compliance Requirements
To support tax positions, maintain:
- Unrealized gain/loss tracker
- Fixed asset register
- Transfer pricing documentation
- Interest limitation workings
- Tax reconciliation statement
- Common Errors Identified in UAE
- Incorrect treatment of unrealized gains
- No adjustment for unrealized losses
- Missing TP documentation
- Ignoring interest limitation
- Incorrect depreciation
- Strategic Insight for UAE Businesses
Realization basis is generally suitable for:
- Real estate developers
- Investment companies
- High foreign exchange exposure entities
- Accrual basis is suitable for:
- Trading companies
- Service providers with stable margins
Practical Considerations
Realization basis is generally more suitable for:
- Real estate and investment entities
- Businesses with significant fair value adjustments
- Entities with foreign currency exposure
- Accrual basis is typically used by:
- Trading and service companies
- Businesses with stable income and minimal revaluation
Conclusion
Unrealized gains and losses represent timing differences under UAE Corporate Tax. Proper treatment ensures accurate taxable income, compliance with legal requirements, and reduced exposure to tax adjustments.
Need Help with UAE Corporate Tax?
Ensure your Corporate Tax computation is accurate, compliant, and optimized.
- ✔ Corporate Tax Calculation & Filing
- ✔ Unrealized Gain/Loss Tracking
- ✔ Transfer Pricing Compliance
- ✔ FTA Audit Support
Contact TAXPERTISE today for expert UAE Corporate Tax advisory.
Related UAE Tax Services
- UAE Corporate Tax Registration Guide
- Transfer Pricing UAE Guide
- UAE VAT Complete Guide
- Corporate Tax Calculation UAE
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)