
UAE Corporate Tax Alert: Director vs Officer Explained – Avoid Costly Tax Disallowances (CTP010 Guide)
Understand the difference between Director and Officer under UAE Corporate Tax (CTP010). Learn how Connected Person rules under Article 36 impact deductibility, disclosure, and tax risk.

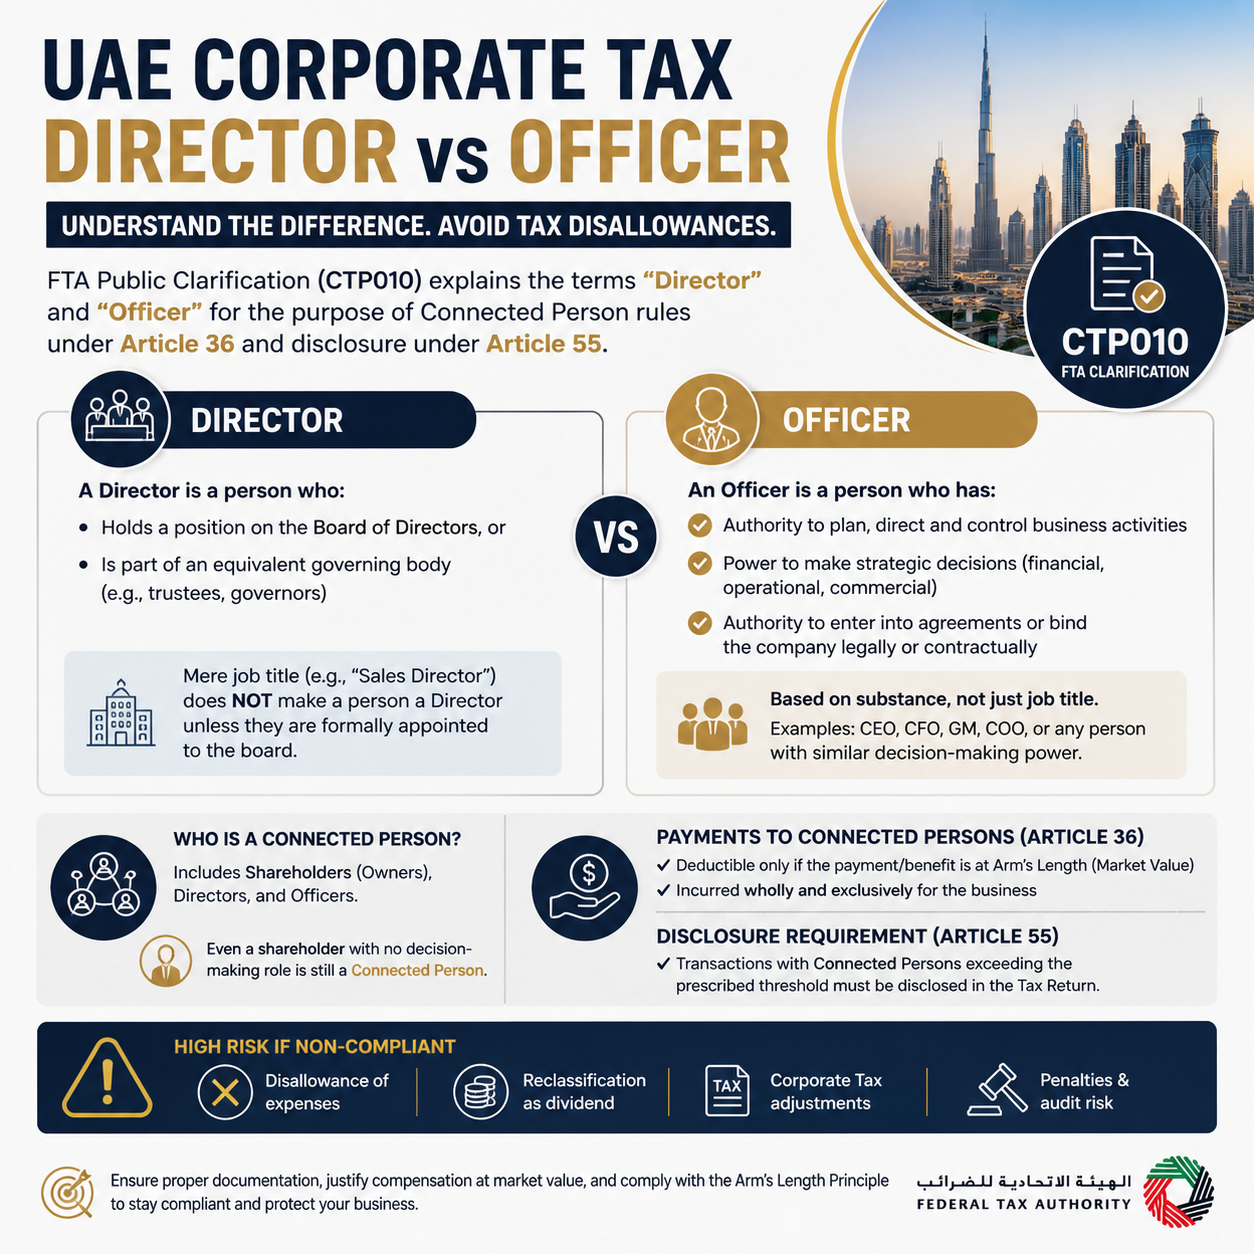
UAE Corporate Tax Alert: Director vs Officer – A Critical Distinction Under CTP010
The UAE Corporate Tax regime, governed by Federal Decree-Law No. 47 of 2022, continues to evolve with detailed guidance from the Federal Tax Authority (FTA). One such critical clarification is CTP010, which explains the distinction between “Director” and “Officer” for the purpose of Connected Person transactions under Article 36.
This distinction is not merely definitional—it directly impacts tax deductibility, transfer pricing compliance, and mandatory disclosures under Article 55.
📌 Why This Clarification Matters
Under Article 36 of the UAE Corporate Tax Law, any payment made to a Connected Person is:
- ✔ Deductible only if it meets the Arm’s Length Principle
- ✔ Subject to strict scrutiny by the FTA
- ✔ Potentially disallowed if excessive or unjustified
Additionally, under Article 55, such transactions may require mandatory disclosure in the Tax Return.
👤 Who is a “Director”?
According to CTP010, a Director is a person who:
- ✔ Holds a position on the Board of Directors, or
- ✔ Is part of an equivalent governing body (e.g., trustees, governors)
❗ Important: A job title alone (e.g., “Sales Director”) does not qualify a person as a Director unless they are formally appointed to the board.
🧑💼 Who is an “Officer”?
The term Officer is broader and based on substance over form.
A person is considered an Officer if they have:
- ✔ Authority to plan, direct, and control business activities
- ✔ Power to make strategic decisions (financial, operational, commercial)
- ✔ Authority to bind the company legally or contractually
Typical examples include:
- CEO (Chief Executive Officer)
- CFO (Chief Financial Officer)
- GM (General Manager)
- COO / CCO
❗ Even without a formal title, a person may still be classified as an Officer based on their actual authority.
⚠️ Connected Person Risk – Ownership Alone is Enough
A key takeaway from Article 36(2) is that a Connected Person includes:
- ✔ Shareholders (owners)
- ✔ Directors
- ✔ Officers
➡️ This means even a 50% shareholder with no decision-making role is still a Connected Person.
💣 High-Risk Areas Identified by FTA
- ⚠️ Salaries paid to passive shareholders
- ⚠️ Management fees without actual services
- ⚠️ Inflated compensation to key executives
- ⚠️ Family-owned business arrangements
Such payments are likely to be:
- ❌ Disallowed as deductible expenses
- ❌ Reclassified as dividends
- ❌ Subject to Corporate Tax adjustments
📊 Practical Example
A shareholder holding 50% ownership receives AED 1 million annually labeled as “management fees” but has no involvement in decision-making.
- ➡️ Not a Director ❌
- ➡️ Not an Officer ❌
- ➡️ Still a Connected Person ✅
👉 Result: The payment may be fully disallowed unless justified at market value.
🧠 Expert Insight
The FTA is clearly adopting a substance-over-form approach. Businesses must:
- ✔ Document roles and responsibilities
- ✔ Justify compensation using benchmarking
- ✔ Ensure compliance with Arm’s Length Principle
📢 Final Thoughts
The distinction between Director and Officer is no longer theoretical—it has direct tax consequences.
Businesses operating in the UAE must reassess:
- ✔ Compensation structures
- ✔ Shareholder arrangements
- ✔ Governance frameworks
Failure to comply may result in tax disallowances, penalties, and increased audit risk.
🔗 For official guidance, refer to the FTA Public Clarification (CTP010).
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)