
UAE Corporate Tax Explained | 9% Tax on Profit, Not Turnover
Confused whether UAE Corporate Tax is charged on turnover or profit? Learn how the 9% Corporate Tax is calculated, the AED 375,000 exemption, and how non-qualifying income is taxed.

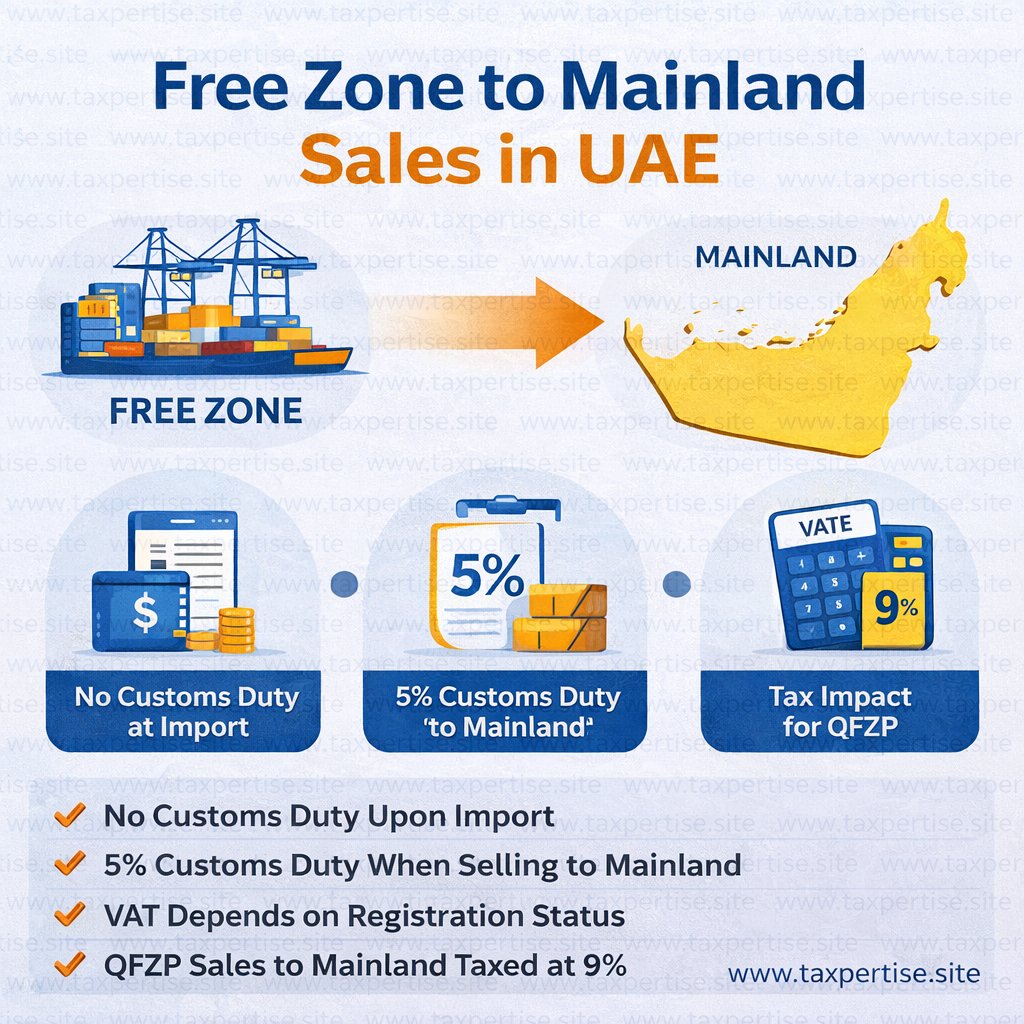
UAE Corporate Tax: Is 9% Charged on Turnover or Profit?
One of the most common misunderstandings under the UAE Corporate Tax law is whether the 9% Corporate Tax is charged on total income or on profit. This confusion is especially common among Free Zone businesses earning non-qualifying income.
The answer is clear: UAE Corporate Tax is charged on taxable profit, not on turnover.
What Is Taxable Profit Under UAE Corporate Tax?
Taxable profit is broadly based on the company’s accounting profit, adjusted for items required under the UAE Corporate Tax law.
In simple terms:
Taxable Profit = Total Income – Allowable Expenses
This means Corporate Tax is applied only after deducting business expenses such as:
- Cost of goods sold
- Operating expenses
- Employee costs
- Rent, logistics, and administrative expenses
AED 375,000 Corporate Tax Exemption Explained
All UAE businesses (including Free Zone companies) benefit from a Corporate Tax exemption on the first AED 375,000 of taxable profit.
- First AED 375,000 of taxable profit: 0% tax
- Taxable profit above AED 375,000: 9% tax
This exemption applies to profit, not to revenue.
Does Non-Qualifying Income Mean 9% on Total Revenue?
No. This is a critical misconception.
If a business earns non-qualifying income (for example, B2C sales through Amazon or Noon), this does not mean that 9% tax applies on total sales.
Corporate Tax is still calculated as follows:
- Determine taxable profit
- Apply AED 375,000 exemption
- Apply 9% tax on remaining profit
Example: Corporate Tax Calculation
Scenario:
- Total revenue: AED 1,200,000
- Total expenses: AED 600,000
- Taxable profit: AED 600,000
Corporate Tax calculation:
- AED 375,000 → 0%
- Remaining AED 225,000 → 9%
Corporate Tax payable: AED 20,250
Note: Tax is charged on profit, not on turnover.
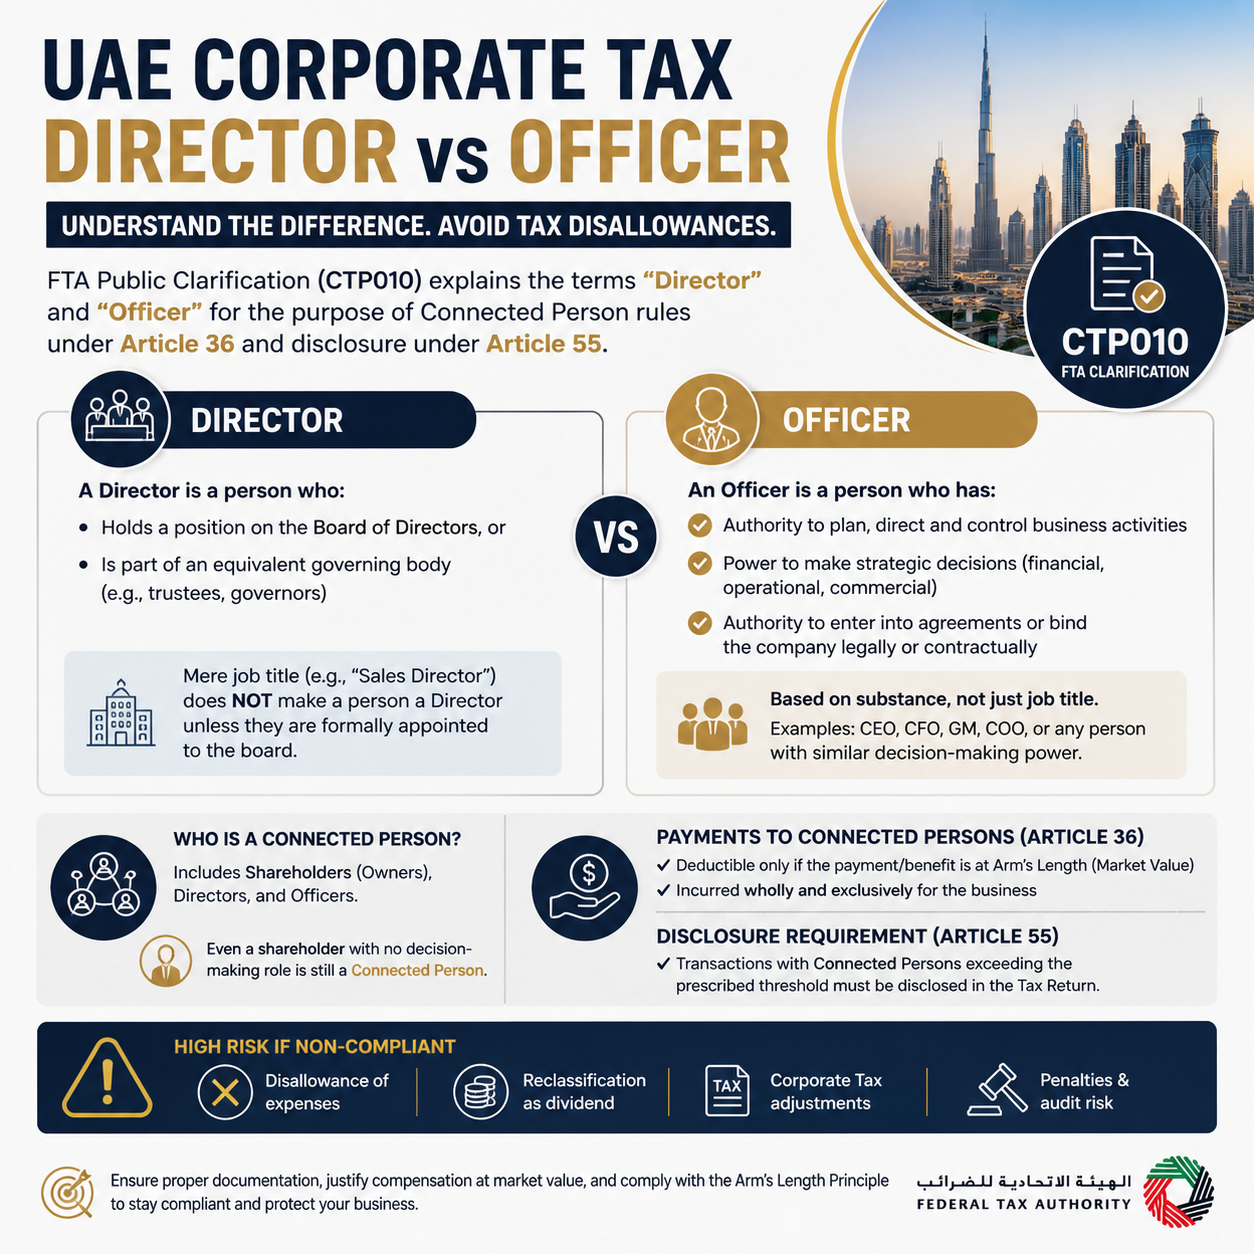
Corporate Tax Treatment for Qualifying Free Zone Persons (QFZP)
A Qualifying Free Zone Person may earn both:
- Qualifying income (taxed at 0%), and
- Non-qualifying income (taxed at 9%)
However:
- Qualifying income remains taxed at 0%
- Non-qualifying income is taxed at 9% (after AED 375,000 exemption)
If non-qualifying income exceeds the permitted threshold (5% of total revenue or AED 5 million, whichever is lower), the QFZP status may be lost.
Key Points to Remember
- UAE Corporate Tax is profit-based, not revenue-based
- The 9% rate applies only above AED 375,000 of taxable profit
- Non-qualifying income does not mean tax on total sales
- VAT rules and VAT thresholds are completely separate from Corporate Tax
Professional Summary
UAE Corporate Tax at 9% is charged on taxable profit exceeding AED 375,000, not on turnover. Even where income is non-qualifying, businesses are taxed only on net profit after allowable deductions, ensuring Corporate Tax remains a profit-based regime.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)