
UAE Corporate Tax Group Formation: Article 40(1) Conditions Explained (2026 Guide)
Understand all conditions under Article 40(1) of UAE Corporate Tax Law for forming a Tax Group. Complete compliance checklist, eligibility criteria, and expert insights.

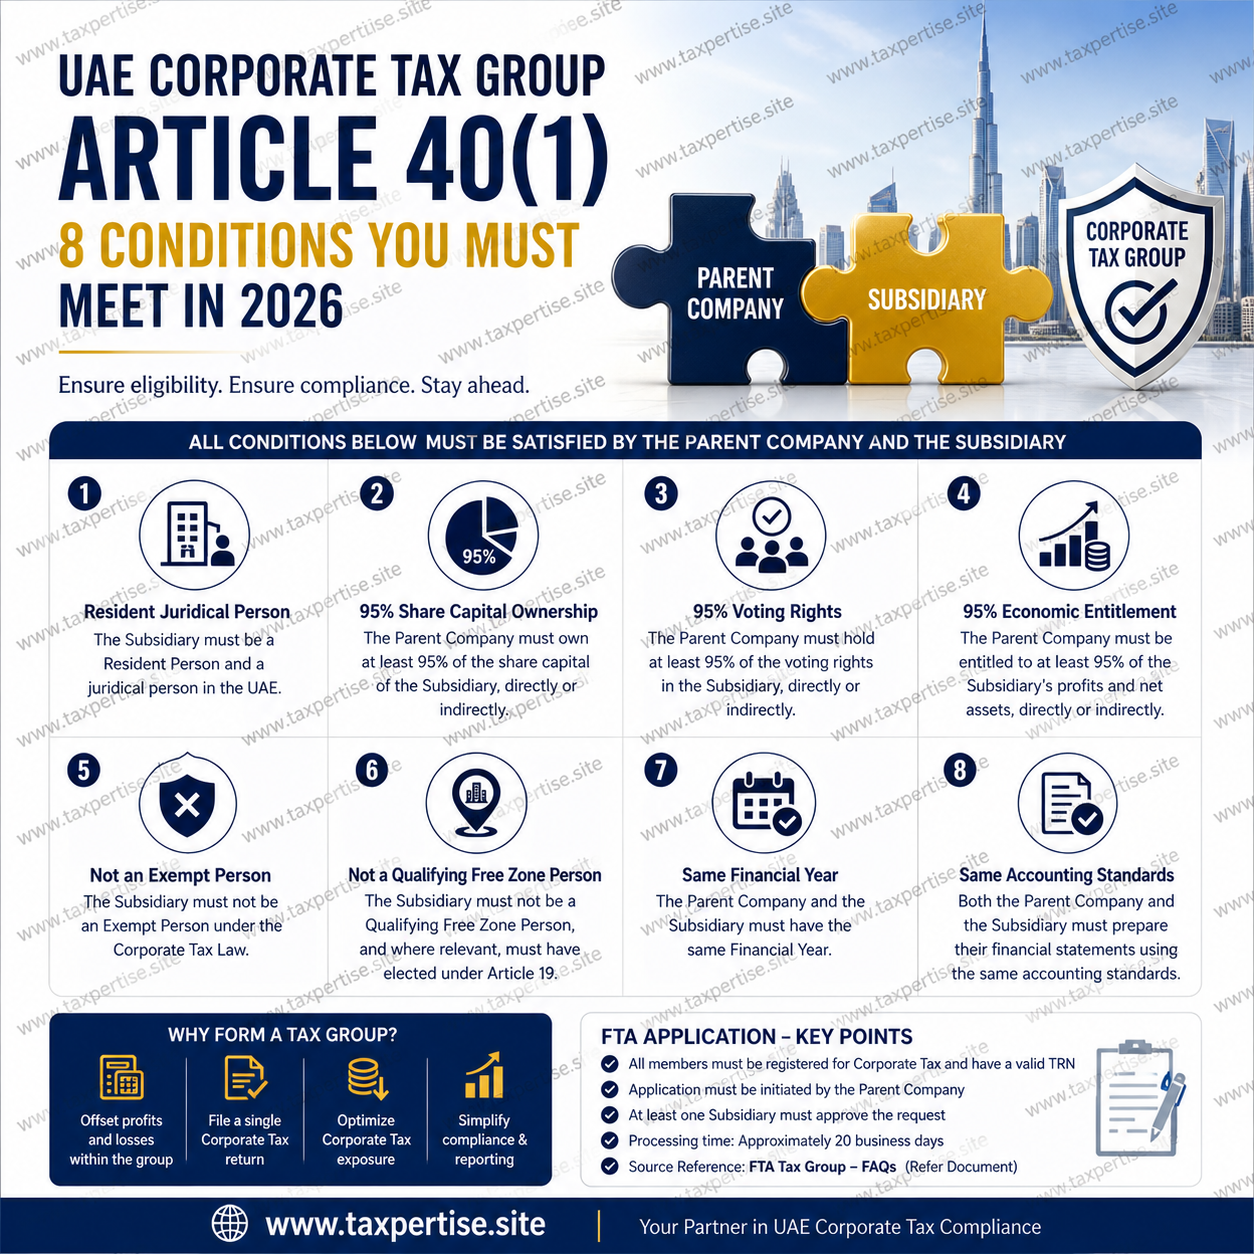
UAE Corporate Tax Group Formation – Article 40(1) Conditions
The introduction of Corporate Tax in the UAE has made Tax Group structuring a critical planning tool for businesses. Under Article 40(1) of the UAE Corporate Tax Law, companies can form a Tax Group subject to strict eligibility conditions.
This guide provides a clear, practical, and compliance-focused breakdown of each requirement to ensure your application is approved without delays.
🔍 Core Conditions for Tax Group Formation
The Subsidiary must meet ALL of the following conditions:
a) Resident Juridical Person
The entity must be a Resident Person and legally established as a juridical person in the UAE. Natural persons are strictly excluded.
b) 95% Share Capital Ownership
The Parent Company must own at least 95% of the share capital, either:
- Directly, or
- Indirectly through other subsidiaries
c) 95% Voting Rights
Control must extend to 95% of voting rights, ensuring effective decision-making authority.
d) 95% Economic Entitlement
The Parent must be entitled to at least:
- 95% of profits
- 95% of net assets
e) Not an Exempt Person
Entities classified as Exempt Persons cannot be part of a Tax Group.
f) Not a Qualifying Free Zone Person (QFZP)
A Subsidiary must NOT be a Qualifying Free Zone Person, unless it has made an election to be taxed at standard Corporate Tax rates.
g) Same Financial Year
Both Parent and Subsidiary must maintain the same financial year. Misalignment leads to automatic rejection.
h) Same Accounting Standards
Uniformity is required in financial reporting standards (e.g., IFRS).
📌 Practical Compliance Insights
- Ownership test is cumulative → Share capital + voting rights + economic entitlement must ALL meet 95%
- Indirect ownership structures are allowed, but must be clearly documented
- Mismatch in accounting standards is a common rejection trigger
- Free Zone entities require careful tax election planning
⚠️ FTA Application Requirements
As per Federal Tax Authority (FTA) procedures:
- All members must have valid Corporate Tax TRNs
- Application must be initiated by the Parent Company
- At least one Subsidiary must approve the request
- Processing timeline: ~20 business days
📄 Source Reference: :contentReference[oaicite:0]{index=0}
🚀 Why Form a Tax Group?
- Offset profits and losses within the group
- Simplify compliance with a single tax return
- Optimize Corporate Tax exposure
- Centralize financial reporting
💡 Expert Takeaway
While the 95% threshold appears straightforward, real-world structures often fail due to indirect ownership gaps, documentation issues, or Free Zone complications.
A pre-assessment review is strongly recommended before submission to avoid rejection or delays.
📞 Need Help with UAE Tax Group Structuring?
We provide end-to-end Corporate Tax advisory, including:
- Eligibility assessment
- Structure optimization
- FTA application support
👉 Contact us today to ensure 100% compliant Tax Group formation.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)