
UAE Corporate Tax: Secondment, CTP010 & Connected Person Rules – The Critical Distinction You Cannot Ignore
Explore how secondment arrangements are treated under UAE Corporate Tax (CTP010). Learn when payments qualify as Connected Person transactions under Articles 35 and 36.

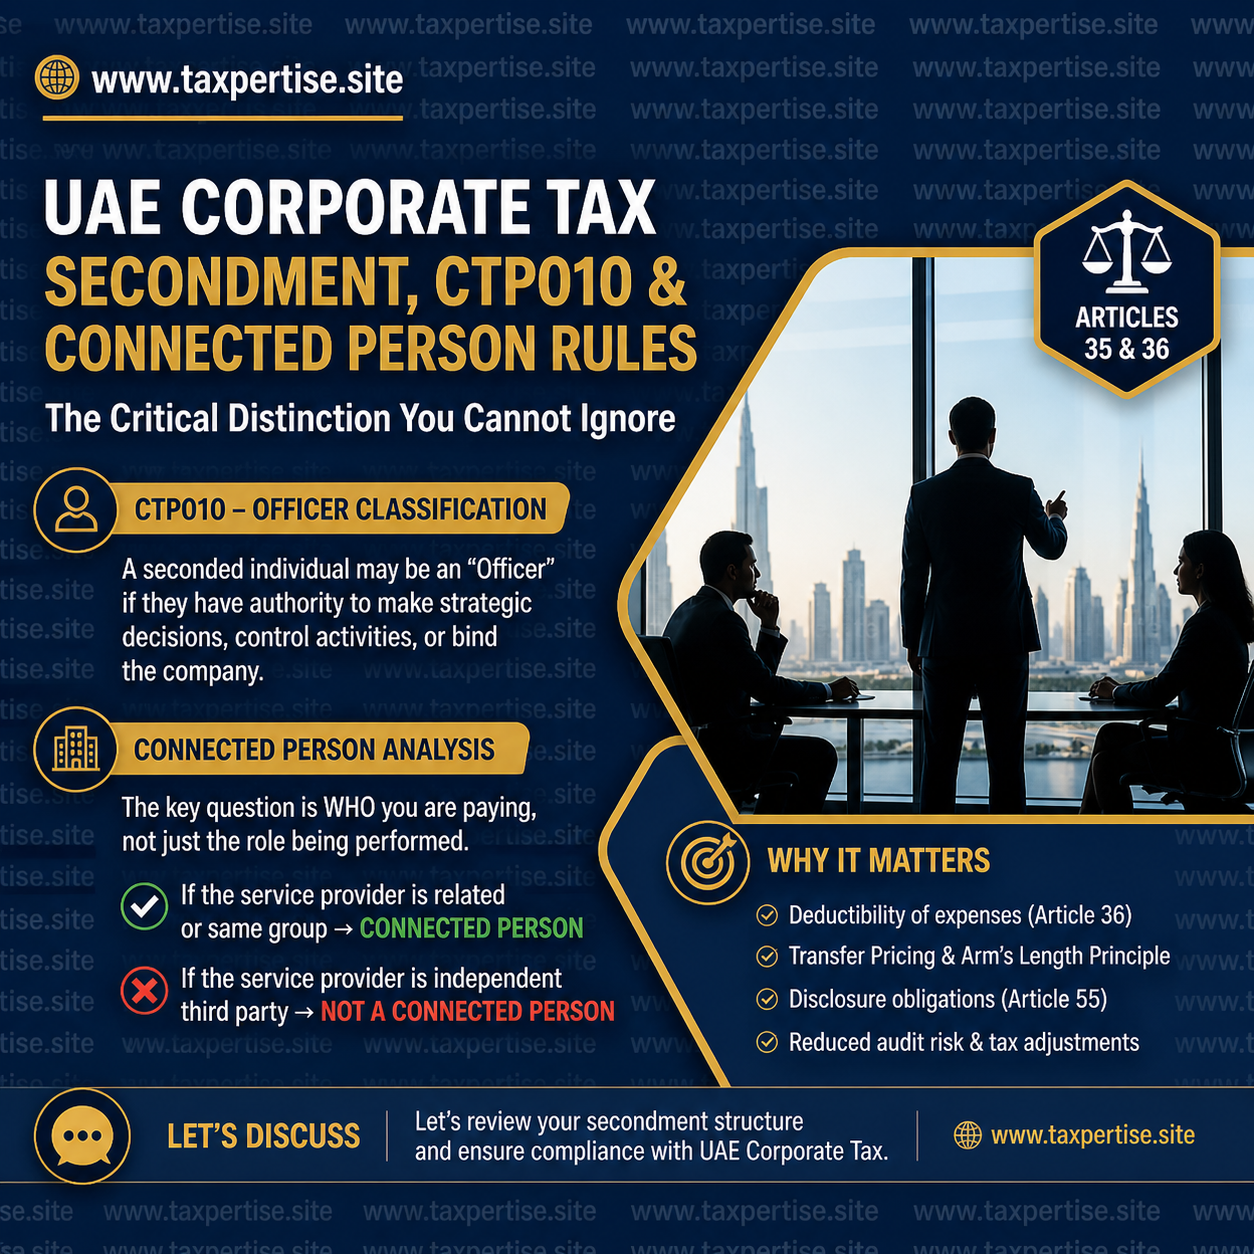
UAE Corporate Tax: Secondment Arrangements Under CTP010 – Are You Exposed?
With the introduction of Corporate Tax in the UAE, businesses are increasingly relying on secondment arrangements to manage operations, particularly at the C-suite level. However, the recent clarification CTP010 issued by the Federal Tax Authority (FTA) has introduced a critical distinction that many taxpayers are overlooking.
The key issue is simple yet highly technical:
Does a seconded executive create a Connected Person transaction?
📌 Understanding CTP010 – “Officer” Classification
Under CTP010, an individual will be classified as an “Officer” if they have the authority to:
- ✔ Plan, direct, and control business activities
- ✔ Make strategic financial, operational, or commercial decisions
- ✔ Legally or contractually bind the company
Importantly, this classification is based on substance over form. Therefore, a seconded individual performing C-suite functions may qualify as an Officer, even if they are not formally employed by the UAE entity.
⚠️ The Critical Distinction – Who Are You Paying?
While the individual may qualify as an Officer, the tax treatment of the arrangement depends on a different question:
Who is receiving the payment?
In most secondment structures, payments are made to the employing entity (i.e., the service provider), not the individual.
📊 Connected Person Analysis Under Articles 35 & 36
Under the UAE Corporate Tax Law:
- A Connected Person includes owners, directors, and officers
- However, the transaction test applies to the counterparty receiving the payment
Accordingly:
- ✔ If the service provider is related or part of the same group → the payment is a Connected Person transaction
- ❌ If the service provider is an independent third party → the payment is not a Connected Person transaction
This remains true even if the seconded individual is effectively acting as a CEO, CFO, or General Manager.
🚨 Why This Matters
This distinction has significant implications for:
- Deductibility of expenses under Article 36
- Transfer Pricing and Arm’s Length Principle
- Disclosure requirements under Article 55
- FTA audit risk and tax adjustments
Misclassification can lead to:
- ❌ Disallowed expenses
- ❌ Recharacterization of payments
- ❌ Increased compliance exposure
🧠 Practical Insight
The FTA’s approach clearly separates:
- Functional analysis → Determines if a person is an Officer
- Relationship analysis → Determines if a payment is a Connected Person transaction
Businesses must ensure that both tests are independently satisfied.
📢 Final Thoughts
Secondment arrangements are no longer a routine operational matter—they are now a Corporate Tax risk area.
Companies operating in the UAE should immediately review:
- ✔ Structure of secondment agreements
- ✔ Nature of authority granted to secondees
- ✔ Relationship with service provider entities
- ✔ Transfer pricing documentation
Ignoring this distinction may result in unexpected tax exposures.
🤝 Let’s Discuss
Are your secondment arrangements compliant with CTP010 and UAE Corporate Tax Law?
Let’s discuss your structure and identify potential risks before the FTA does.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)