
UAE DMTT: FTA Decision No. 12 of 2026 Sets Registration, Deregistration and Notification Deadlines

UAE DMTT: FTA Decision No. 12 of 2026 Sets Registration, Deregistration and Notification Deadlines
The UAE has taken another important step in implementing the Domestic Minimum Top-up Tax (DMTT) under the OECD Pillar Two framework.
Federal Tax Authority Decision No. 12 of 2026 establishes the requirements and timelines for the registration, deregistration and in-scope/out-of-scope notifications of entities subject to the UAE Top-up Tax regime.
The Decision was issued on 16 July 2026 and applies to fiscal years starting on or after 1 January 2025.
Key Takeaway
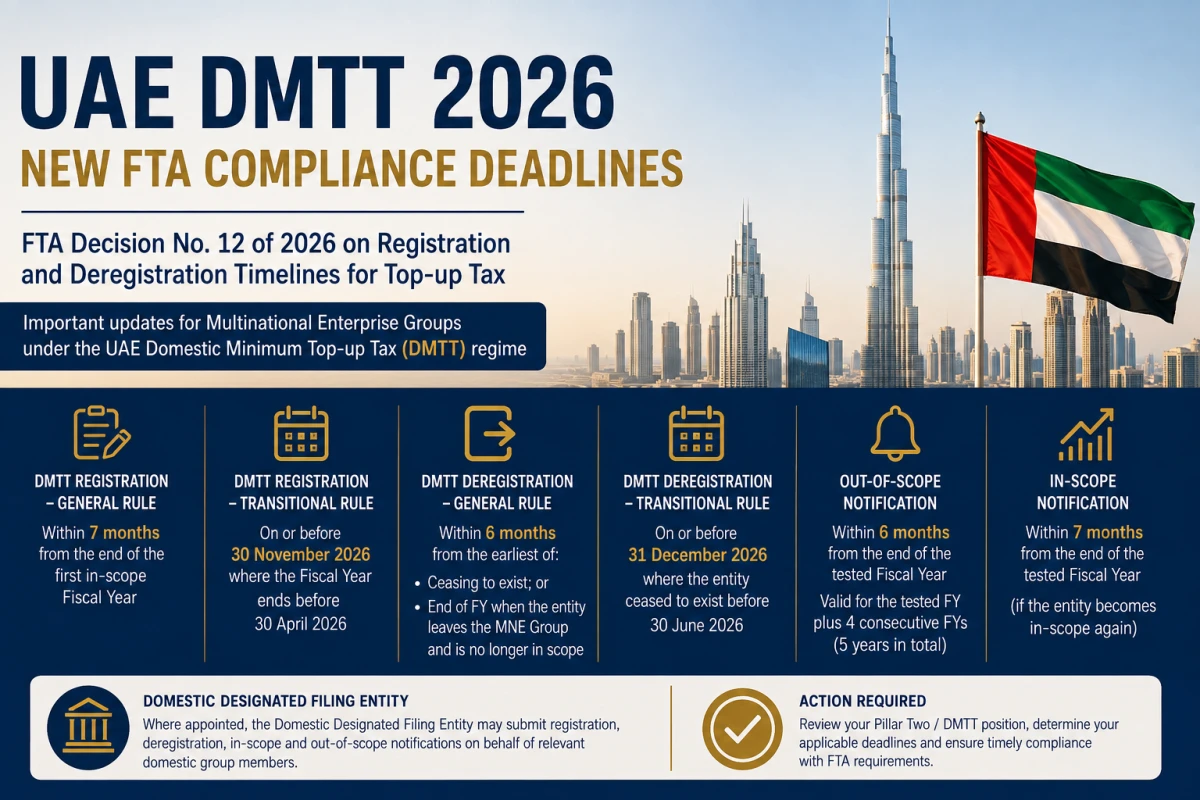
An entity subject to UAE Top-up Tax must generally submit its DMTT tax registration application within seven months from the end of its first in-scope fiscal year.
A special transitional deadline applies to entities with a fiscal year ending before 30 April 2026: their Top-up Tax registration application must be submitted by 30 November 2026.
What Is FTA Decision No. 12 of 2026?
FTA Decision No. 12 of 2026 provides the administrative compliance framework for entities falling within the UAE's Top-up Tax regime under Cabinet Decision No. 142 of 2024 on the Imposition of Top-up Tax on Multinational Enterprises.
The Decision specifically addresses:
- Top-up Tax registration;
- Top-up Tax deregistration;
- Out-of-scope notifications;
- In-scope notifications;
- Special transitional deadlines; and
- Registration and deregistration by a Domestic Designated Filing Entity.
It is important to understand that this Decision primarily establishes compliance timelines and administrative requirements. It does not, by itself, determine whether every UAE business is subject to DMTT.
Who Needs to Consider UAE DMTT Registration?
The Decision applies to entities that are within the scope of the UAE Top-up Tax regime under Cabinet Decision No. 142 of 2024.
Accordingly, businesses should first determine whether their group falls within the relevant Multinational Enterprise Group (MNE Group) scope before determining the applicable registration or notification requirement.
This makes scope assessment the first step in the DMTT compliance process.
DMTT compliance sequence:
Determine MNE Group scope → Determine UAE entity status → Identify applicable notification/registration → Meet FTA deadline → Complete Top-up Tax reporting and payment obligations
UAE DMTT Registration Deadline
Under Article 2 of FTA Decision No. 12 of 2026, an entity that is subject to Top-up Tax must submit its Tax Registration application for Top-up Tax purposes within a period of:
7 months from the end of the first Fiscal Year in which the entity is in scope.
This is one of the most important deadlines introduced by the Decision.
Example
Assume an entity's first fiscal year within the DMTT scope ends on 31 December 2025.
The general registration deadline would therefore be:
31 July 2026.
The calculation is based on the end of the first fiscal year in which the entity is within the applicable Top-up Tax scope.
Special Transitional Deadline – 30 November 2026
FTA Decision No. 12 of 2026 provides a specific transitional rule.
Where an entity has a fiscal year ending before 30 April 2026, the entity must submit its Top-up Tax registration application:
On or before 30 November 2026.
Important: This transitional deadline should not be confused with the general seven-month registration rule. Entities with fiscal years ending before 30 April 2026 are specifically covered by the transitional provision.
DMTT Deregistration Requirements
The Decision also establishes the deadline for deregistration from the UAE Top-up Tax regime.
An entity must submit its Top-up Tax deregistration application within:
6 months from the earliest of the following dates:
- The date the entity ceases to exist; or
- The end of the fiscal year in which the entity leaves the MNE Group and is no longer within the applicable Top-up Tax scope.
Transitional Deregistration Rule
Where an entity ceased to exist before 30 June 2026, the Top-up Tax deregistration application must be submitted on or before:
31 December 2026.
Deregistration Is Not Simply an Administrative Filing
Before an entity can be deregistered for Top-up Tax purposes, the Decision requires the entity to have:
- Settled all Top-up Tax payable;
- Settled all applicable penalties;
- Filed all Top-up Tax Returns due; and
- Filed all required Pillar Two Information Returns.
Therefore, an entity should not treat deregistration as merely closing its FTA registration.
Outstanding Top-up Tax liabilities, penalties or filing obligations can prevent deregistration.
Can the FTA Deregister an Entity?
Yes.
Where a registrant meets the applicable deregistration requirements but has not submitted a deregistration application, the FTA may, at its discretion and based on the information available to it, deregister the entity.
However, entities should not rely on automatic or FTA-initiated deregistration. The appropriate compliance approach is to assess the entity's status and submit the required application within the prescribed deadline.
Out-of-Scope Notification
FTA Decision No. 12 of 2026 also introduces specific requirements for entities that are members of an MNE Group where the group ceases to be within the relevant Top-up Tax scope for a tested fiscal year.
The entity must submit an out-of-scope notification within six months from the end of the tested fiscal year.
How Long Does an Out-of-Scope Notification Remain Valid?
An out-of-scope notification remains valid for:
The tested fiscal year plus the following four consecutive fiscal years.
In other words, an out-of-scope notification can remain effective for a total period of five consecutive fiscal years, unless an in-scope notification becomes necessary earlier.
What Happens If the Entity Becomes In-Scope Again?
An entity may subsequently become subject to the DMTT regime after previously submitting an out-of-scope notification.
Where the entity is in scope in a tested fiscal year and its previous out-of-scope notification remains valid, it must submit an in-scope notification within seven months from the end of the tested fiscal year.
This means businesses should not assume that an earlier out-of-scope notification permanently removes their DMTT compliance obligations.
Five-Year Out-of-Scope Rule
Where an out-of-scope notification remains valid for five consecutive fiscal years, the entity must submit a Top-up Tax deregistration application within:
6 months from the end of the fifth consecutive fiscal year.
The exception is where the entity becomes subject to an in-scope notification requirement.
Domestic Designated Filing Entity
FTA Decision No. 12 of 2026 provides an important compliance mechanism for groups that have appointed a Domestic Designated Filing Entity.
Where such an entity has been appointed under Cabinet Decision No. 142 of 2024, it may submit the relevant:
- Top-up Tax registration application;
- Top-up Tax deregistration application;
- In-scope notification; and
- Out-of-scope notification
on behalf of the relevant members of:
- A Domestic Main Group;
- A Domestic Minority-owned Subgroup;
- A Reverse Hybrid Entity; or
- A Domestic JV Group.
This mechanism can significantly affect how multinational groups should organise their UAE DMTT compliance process.
Key UAE DMTT Deadlines at a Glance
| Compliance Requirement | Deadline |
|---|---|
| DMTT Registration – General Rule | Within 7 months from the end of the first in-scope Fiscal Year |
| DMTT Registration – Transitional Rule | On or before 30 November 2026 where the Fiscal Year ends before 30 April 2026 |
| DMTT Deregistration – General Rule | Within 6 months from the earliest applicable cessation / exit date |
| DMTT Deregistration – Transitional Rule | On or before 31 December 2026 where the entity ceased to exist before 30 June 2026 |
| Out-of-Scope Notification | Within 6 months from the end of the tested Fiscal Year |
| In-Scope Notification | Within 7 months from the end of the tested Fiscal Year |
| Deregistration after 5 consecutive out-of-scope years | Within 6 months from the end of the fifth consecutive Fiscal Year |
What Should UAE MNE Groups Do Now?
Businesses potentially affected by UAE DMTT should not wait until the filing deadline to determine their obligations.
A practical DMTT compliance review should include the following steps:
- Identify the MNE Group.
Determine whether the UAE entity forms part of an MNE Group relevant to the Pillar Two framework. - Assess DMTT scope.
Determine whether the group falls within the applicable Top-up Tax scope under Cabinet Decision No. 142 of 2024. - Determine the UAE entity's status.
Identify whether the entity is subject to registration, notification or another compliance requirement. - Determine the relevant fiscal year.
The applicable deadline depends heavily on the entity's fiscal year and its in-scope/out-of-scope status. - Check whether a Domestic Designated Filing Entity has been appointed.
Where applicable, the designated entity may handle registration and notification requirements for relevant domestic group members. - Track the applicable deadline.
Maintain a DMTT compliance calendar covering registration, notification, return and payment obligations.
Why FTA Decision No. 12 of 2026 Matters
The significance of FTA Decision No. 12 of 2026 is that the UAE DMTT framework is moving beyond legislation and into practical administrative compliance.
For multinational groups, determining whether DMTT applies is only the beginning.
Once an entity is within scope, the group needs to consider:
- Registration;
- In-scope and out-of-scope notifications;
- Top-up Tax Returns;
- Pillar Two Information Returns;
- Top-up Tax liabilities;
- Payment obligations;
- Deregistration where applicable; and
- Ongoing monitoring of the group's Pillar Two status.
Conclusion
FTA Decision No. 12 of 2026 provides the operational deadlines for UAE Top-up Tax registration, deregistration and in-scope/out-of-scope notifications.
The most important deadline for newly in-scope entities is the seven-month registration period from the end of the first in-scope fiscal year. However, entities with fiscal years ending before 30 April 2026 are subject to the special transitional registration deadline of 30 November 2026.
Similarly, entities leaving the DMTT regime need to carefully monitor the six-month deregistration requirement, while groups that move between in-scope and out-of-scope positions must monitor their notification obligations.
For UAE businesses forming part of multinational groups, DMTT compliance should therefore be treated as an ongoing Pillar Two compliance process rather than a one-time registration exercise.
Need Assistance With UAE DMTT / Pillar Two Compliance?
Taxpertise can assist multinational groups and UAE entities with DMTT scope assessment, Pillar Two compliance, registration requirements, in-scope/out-of-scope analysis and ongoing UAE Top-up Tax compliance.
Contact us to assess whether your UAE entity is affected by the Domestic Minimum Top-up Tax regime.
Official FTA Reference
Source: Federal Tax Authority, FTA Decision No. 12 of 2026, issued 16 July 2026. The Decision is an unofficial English translation published by the FTA; the Arabic version should be referred to where legal interpretation is required.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)