
UAE VAT Update: New Rules on Recovering VAT on Employee Expenses from 1 October 2026
The UAE Federal Tax Authority has issued FTA Decision No. 17 of 2026, introducing specific rules on when businesses may recover input VAT on goods and services provided to employees free of charge.

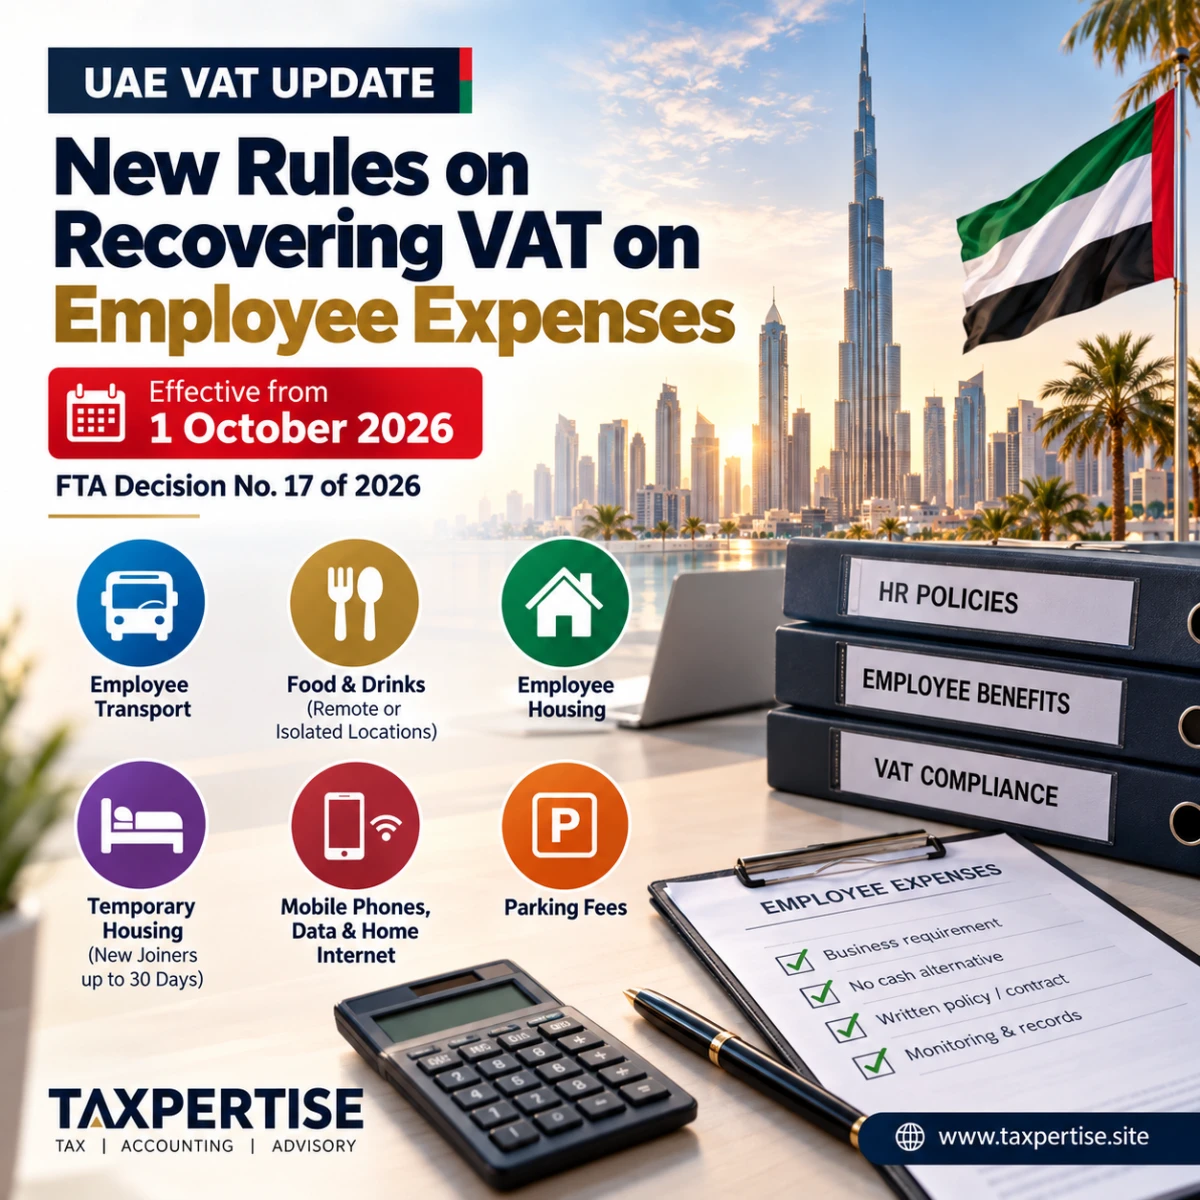
What employee expenses are covered?
The Decision addresses six categories:
- 🚐 Employee transportation
- 🍽️ Food and drinks provided in remote or isolated locations
- 🏠 Employee accommodation
- 🧳 Temporary accommodation for new employees — up to 30 days
- 📱 Mobile phones, data and home internet
- 🅿️ Parking fees
The important point is that VAT recovery is not automatic.
Each category has its own conditions, and the relevant requirements must be satisfied before input VAT can be recovered.
Common conditions businesses should look at
Across the different categories, businesses should pay particular attention to whether:
✔️ The employee cannot choose a cash allowance instead of the benefit.
✔️ The benefit is provided because of a business requirement, rather than simply as a personal benefit.
✔️ There is an appropriate contract, agreement or written company policy supporting the arrangement.
✔️ The business has appropriate controls, monitoring and records to support the VAT recovery.
Why does this matter?
Employee-related expenses can represent significant input VAT for businesses, particularly where they provide accommodation, transportation, telecommunications or other employee facilities.
But simply having a tax invoice is not enough.
The business needs to demonstrate that the expense falls within the relevant conditions under the Decision.
This means that Tax, Finance and HR should look at these arrangements together, rather than treating them as purely payroll or HR matters.
Practical checklist for businesses
Before recovering VAT on employee-related expenses, consider:
1. What is the expense?
Identify which of the six categories it falls under.
2. Why is the benefit being provided?
Document the underlying business requirement.
3. Is there an alternative cash allowance?
Check whether employees can opt for cash instead.
4. Is there a written policy or contractual basis?
Make sure the arrangement is properly documented.
5. Is usage being monitored?
Maintain sufficient records to demonstrate compliance.
6. Is the input VAT supported by proper documentation?
Keep the relevant tax invoices and supporting evidence.
Key takeaway
The new rules create an important opportunity for businesses to review employee-related input VAT recovery — but they also introduce a need for better documentation and internal controls.
If your business provides employee accommodation, transport, telecommunications, meals or parking, this is a good time to review the arrangements before the VAT return is prepared.
Don't wait until an FTA review to discover that the supporting evidence isn't there.
Official reference
FTA Decision No. 17 of 2026 — Input Tax Recovery in Respect of Certain Goods and Services Provided to Employees
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)