
UAE Excise Tax on Sweetened Drinks 2026 | Tiered Volumetric Model
Executive summary of UAE Excise Tax on Sweetened Drinks effective 1 January 2026, introducing a tiered volumetric tax model based on sugar content.

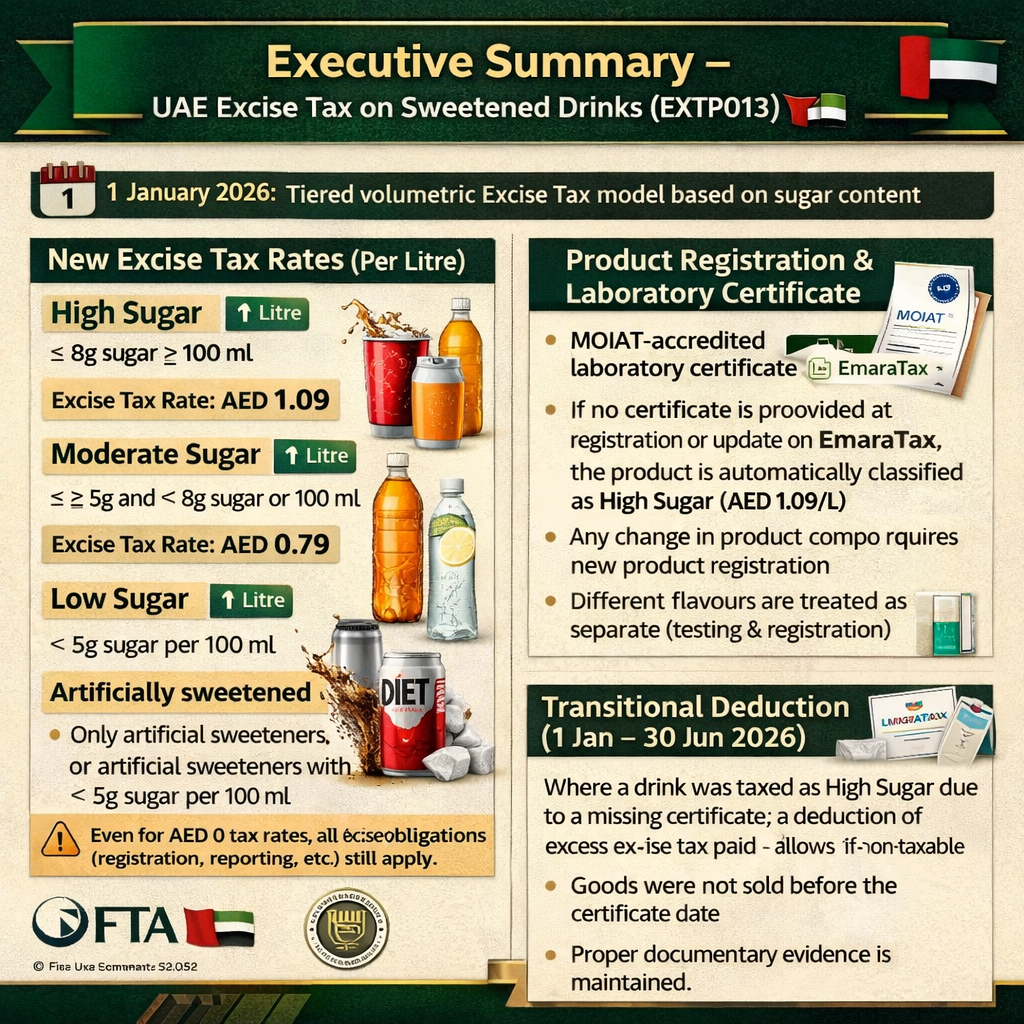
Executive Summary – UAE Excise Tax on Sweetened Drinks (EXTP013)
Effective from 1 January 2026, the UAE Federal Tax Authority (FTA) introduces a tiered volumetric excise tax model for Sweetened Drinks, replacing the existing value-based excise system.
Effective Date
The new Excise Tax framework applies to Sweetened Drinks from 1 January 2026.
New Excise Tax Rates (Per Litre)
High Sugar Content
- ≥ 8g sugar per 100 ml
- Excise Tax Rate: AED 1.09 per litre
Moderate Sugar Content
- ≥ 5g and < 8g sugar per 100 ml
- Excise Tax Rate: AED 0.79 per litre
Low Sugar Content
- < 5g sugar per 100 ml
- Excise Tax Rate: AED 0
Artificially Sweetened Drinks
- Only artificial sweeteners, or artificial sweeteners with < 5g sugar per 100 ml
- Excise Tax Rate: AED 0
Important: Even where the Excise Tax rate is AED 0, all excise compliance obligations (product registration, return filing, reporting) continue to apply.
Product Registration and Laboratory Certification
A MOIAT-accredited laboratory certificate is mandatory to confirm sugar and sweetener content.
- If no certificate is uploaded during registration or update on EmaraTax, the product is automatically classified as High Sugar (AED 1.09/L)
- Any change in product composition requires new product registration
- Different flavours are treated as separate excisable products
- Different pack sizes of the same drink may rely on one laboratory certificate
Transitional Deduction Period (1 January – 30 June 2026)
Where a drink was initially taxed as High Sugar due to a missing certificate, a deduction of excess excise tax paid may be claimed only if all conditions below are met:
- The laboratory certificate later confirms a lower sugar category or non-taxable status
- The goods were not sold before the certificate issuance date
- Proper documentary evidence is maintained
No deduction is permitted if the certificate is obtained after 30 June 2026.
Concentrates, Powders, Gels and Extracts
Sugar content is assessed based on the ready-to-drink beverage, following the producer’s preparation instructions.
If preparation instructions are missing or unreliable, the FTA applies a prescribed calculation method based on:
- Sugar content per unit
- Dilution factor
By default, excise tax is calculated at the Moderate Sugar rate (AED 0.79/L), unless an exception applies.
Exceptions
- Liquid concentrate with < 5g sugar per 100 ml → Low Sugar (AED 0)
- Products containing only artificial sweeteners → AED 0
Stockpiling Considerations
Businesses holding Sweetened Drinks as at 1 January 2026 must assess whether they qualify as stockpilers under UAE Excise Tax rules (refer to EXTP003).
Key Takeaway
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)