
UAE Corporate Tax: Related Party & Connected Person Transactions – Impact of Director/Shareholder Balances in Financial Statements
Understand the UAE Corporate Tax treatment of related party and connected person transactions, especially director and shareholder balances in financial statements. Learn key risks, FTA adjustments, and compliance strategies.

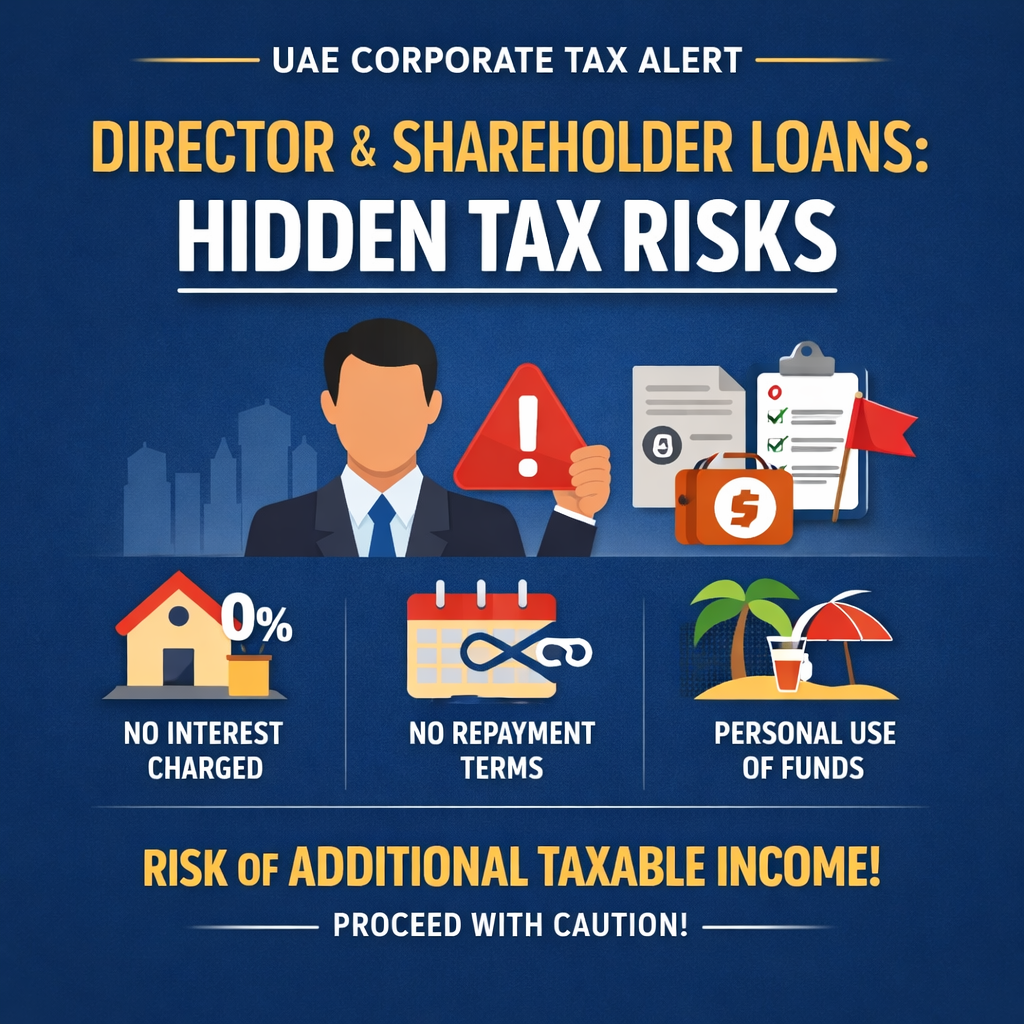
UAE Corporate Tax: Related Party & Connected Person Transactions – Director/Shareholder Balances Explained
A technical guide to understanding how director and shareholder balances impact UAE Corporate Tax, including transfer pricing adjustments, connected person rules, and FTA compliance requirements.
Understanding the Legal Framework
What is a Related Party under UAE Corporate Tax?
Definition, scope, and transfer pricing relevance.
What is a Connected Person?
Definition including directors, shareholders, relatives, and controlled entities.
Key Differences Between Related Party and Connected Person
Comparison based on scope, applicability, and tax treatment.
Types of Director and Shareholder Balances
Director/Shareholder Payable (Loan to Company)
When the company owes money to a director or shareholder.
Director/Shareholder Receivable (Loan from Company)
When a director or shareholder owes money to the company.
Mixed Current Accounts
Combined balances including salary, expenses, and loans.
Corporate Tax Implications and Adjustments
Application of Arm’s Length Principle
Ensuring all transactions reflect market value.
Notional Interest Adjustments
Imputed income on interest-free or below-market loans.
Expense Deductibility Rules
Wholly and exclusively for business requirement.
Reclassification Risks
Potential treatment as dividend, salary, or equity contribution.
Impact on UAE Corporate Tax Return
Adjustments to Taxable Income
- Addition of notional interest income
- Disallowance of non-business expenses
- Removal of excessive interest expense
Illustrative Example
Loan to shareholder: AED 1,000,000
Market interest: 5%
Charged: 0%
Adjustment: AED 50,000 added to taxable income.
Compliance and Documentation Requirements
Transfer Pricing Documentation
Master file and local file requirements where applicable.
Disclosure in Corporate Tax Return
Mandatory reporting of related party transactions.
Supporting Documentation
- Loan agreements
- Interest benchmarking (EIBOR or equivalent)
- Board approvals
FTA Audit Risk Indicators
- Large receivables from shareholders
- No interest charged on loans
- Long outstanding balances
- No repayment schedule
- Personal expenses recorded in company books
Best Practices for Businesses
For Payables (Director to Company)
- Maintain formal agreements
- Apply reasonable interest rates
For Receivables (Company to Director)
- Charge market-based interest
- Define repayment terms
- Avoid personal usage
For Current Accounts
- Segregate transactions clearly
- Perform periodic reconciliation
Conclusion: Key Corporate Tax Risk Area
The highest Corporate Tax exposure arises from receivables due from directors and shareholders, particularly where no interest is charged or repayment terms are unclear. Proper structuring and documentation are essential for compliance and audit readiness.
Frequently Asked Questions (FAQs)
What is a connected person under UAE Corporate Tax?
A connected person includes owners, directors, shareholders, their relatives, and entities they control.
Are director loans taxable?
Not directly, but adjustments may apply if loans are not at market terms.
What is notional interest?
It is deemed income calculated on interest-free or below-market loans.
Are related party transactions mandatory to disclose?
Yes, disclosure in the Corporate Tax return is required.
What is the biggest risk area?
Receivables from shareholders without proper commercial terms.
Quick Answers
- Connected person = ownership/control, not salary
- Interest-free director loans → taxable adjustment risk
- Market value rule applies strictly
- Receivables from shareholders = highest audit exposure
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)