
Do c in UAE? Legal Requirements, Penalties & FTA References
Learn whether offshore companies like JAFZA Offshore and RAK ICC must register for UAE Corporate Tax. Detailed legal references, AED 10,000 penalty rules, FTA compliance guidance, and expert UAE tax analysis.

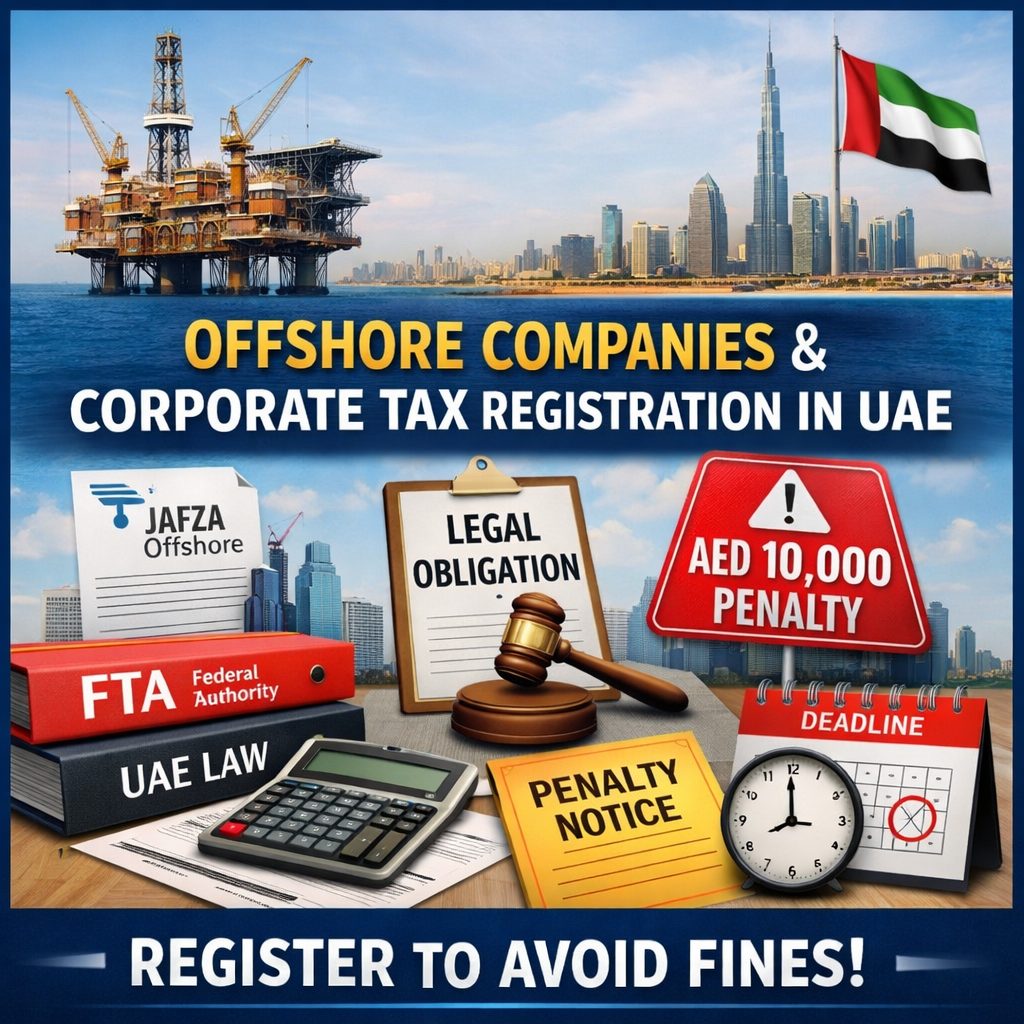
Do Offshore Companies Need Corporate Tax Registration in UAE?
Many business owners believe that an Offshore company is automatically outside the scope of UAE Corporate Tax. However, under Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses, most offshore entities incorporated in the UAE are considered Resident Juridical Persons and therefore must complete Corporate Tax Registration with the Federal Tax Authority (FTA).
Legal Requirement for Offshore Companies to Register
According to Article 11 of the UAE Corporate Tax Law, any juridical person incorporated or established in the UAE is treated as a Resident Person. This includes offshore entities such as JAFZA Offshore, RAK ICC Offshore, and Ajman Offshore companies.
Furthermore, Article 51 requires Taxable Persons to register with the FTA and obtain a Corporate Tax Registration Number.
Official reference: Federal Tax Authority – UAE Corporate Tax Guidance
Important Clarification
Even if the offshore company:
- Has no business activity
- Is a holding company only
- Earns no income in UAE
- Is dormant or inactive
It may still be required to register because legal incorporation in the UAE triggers registration obligations.
Corporate Tax Registration Deadlines
The Federal Tax Authority issues specific registration deadlines based on:
- Incorporation or license issuance date
- FTA notification schedule
- Compliance timelines announced by the Ministry of Finance
Failure to register within the required period may result in administrative penalties.
Penalty for Not Registering Corporate Tax (AED 10,000)
Under Cabinet Decision No. 75 of 2023 and updates introduced through Cabinet Decision No. 10 of 2024, a fixed administrative penalty applies for late Corporate Tax registration.
Key Penalty Details
- AED 10,000 administrative penalty for late registration
- Additional penalties may apply for late filing of Corporate Tax returns
- Compliance risk increases during banking reviews or regulatory audits
Official Ministry of Finance announcement: AED 10,000 Penalty for Late Corporate Tax Registration
Additional Compliance Risks for Offshore Companies
If an offshore entity ignores Corporate Tax obligations, the following risks may arise:
- Late filing penalty starting from AED 500 per month
- Increased scrutiny by financial institutions
- Potential restrictions during license renewals
- Record-keeping and reporting violations under UAE tax procedures
Penalty Waiver Initiative by the Federal Tax Authority
The FTA introduced a relief initiative allowing businesses to request waiver or refund of late registration penalties if certain conditions are met.
- Register for Corporate Tax
- Submit the first Corporate Tax return within 7 months from the end of the first tax period
More details: FTA Penalty Waiver Initiative
When Offshore Companies May Not Need to Register
In limited situations, registration may not be required where:
- The entity is not incorporated in the UAE, and
- It has no Permanent Establishment or UAE-sourced income.
However, most UAE offshore structures still fall under the registration requirement because they are legally established within UAE jurisdictions.
Expert UAE Tax Perspective
Current UAE enforcement follows a clear principle: “Register first, determine taxability later.”
Therefore, offshore companies should complete Corporate Tax registration early to avoid administrative penalties and ensure compliance with UAE tax regulations.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)