
Free Zone Holding Company with No Activity: Can It Qualify as a QFZP in UAE Corporate Tax?
Can a Free Zone holding company with no revenue or activity qualify as a QFZP in UAE Corporate Tax? Learn substance requirements, qualifying income rules, and compliance criteria.

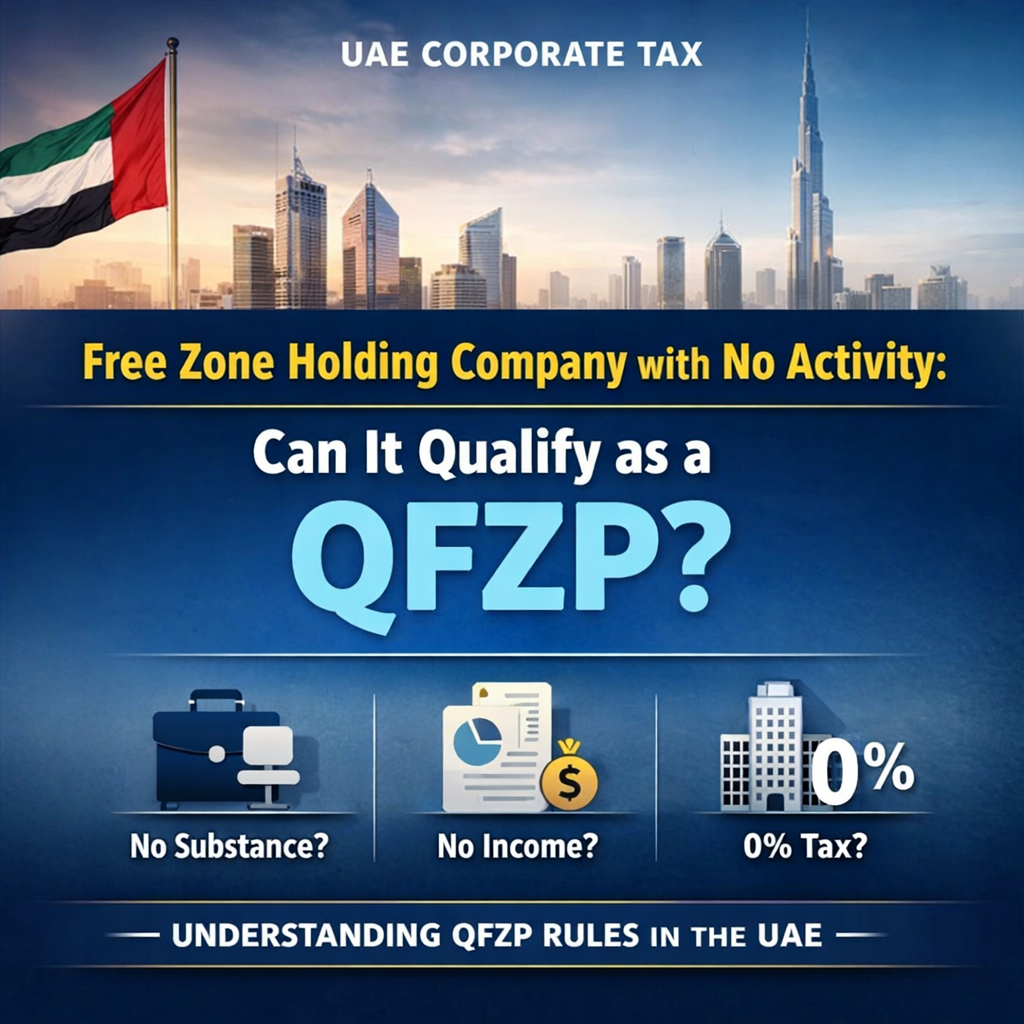
Free Zone Holding Company with No Activity: Can It Qualify as a QFZP?
A common question under UAE Corporate Tax is whether a Free Zone holding company with no revenue, no commercial activity, and no employees can still qualify as a Qualifying Free Zone Person (QFZP) and benefit from the 0% Corporate Tax regime.
The short answer is: No — not without meeting substance requirements. However, the detailed analysis requires a deeper understanding of qualifying conditions, economic substance, and investment rules.
Understanding QFZP Under UAE Corporate Tax
A Free Zone entity can benefit from a 0% Corporate Tax rate only if it qualifies as a Qualifying Free Zone Person (QFZP). This is governed by:
- Cabinet Decision No. 100 of 2023 (Qualifying Income)
- Ministerial Decision No. 261 of 2024 (Free Zone conditions)
To qualify, the entity must meet all conditions simultaneously.
Key Conditions to Qualify as a QFZP
1. Adequate Economic Substance in the UAE
Even for a pure holding company, the law requires maintaining adequate substance in the UAE.
Although reduced requirements apply, the entity must still demonstrate:
- Management and control exercised in the UAE
- Board meetings conducted within the Free Zone
- Decision-making related to investments
- Maintenance of records within the UAE
Important: A company with zero substance will fail this condition immediately.
2. Earning Qualifying Income
For holding companies, qualifying income typically includes:
- Dividends from shares
- Capital gains from ownership interests
These must meet specific criteria under UAE Corporate Tax regulations.
3. Investment Conditions
To treat investment income as qualifying:
- Investments must fall within specified asset classes
- They must be held or intended to be held for at least 12 months
This condition is critical for determining tax treatment of income, but does not replace substance requirements.
4. Compliance Requirements
- Transfer pricing compliance
- Proper documentation and record keeping
- No election to be taxed at the standard 9% rate
Can a Holding Company with No Activity Qualify?
If a Free Zone company has:
- No revenue
- No commercial activity
- No employees
- No economic substance
Then it cannot qualify as a QFZP.
While a holding company benefits from relaxed substance requirements, it is not exempt from substance altogether.
Minimum Substance for Holding Companies
A defensible position for a holding company includes:
- Board meetings held in the UAE
- Strategic decisions taken locally
- Control and management of investments within the UAE
- Basic administrative presence
This represents a minimum viable substance model, not a zero-substance structure.
Key Takeaway
A Free Zone holding company can qualify as a QFZP, but only if it demonstrates:
- Adequate economic substance in the UAE
- Compliance with Corporate Tax conditions
- Qualifying income (where applicable)
Without substance, even a holding company with perfectly structured investments will not be eligible for the 0% Corporate Tax regime.
Need Professional Guidance?
If you are assessing your Free Zone structure or planning to optimize your Corporate Tax position, it is critical to establish a defensible QFZP status.
Contact us for a detailed assessment and advisory tailored to your structure.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)