
UAE Corporate Tax Alert: Foreign Exchange Gain on Dividend Receivable — Taxable or Exempt?
Learn how foreign exchange gains on dividend receivable are treated under UAE Corporate Tax. Understand participation exemption, qualifying income conditions, and whether your FX gains are taxable or exempt.


UAE Corporate Tax: Is Foreign Exchange Gain on Dividend Receivable Taxable or Exempt?
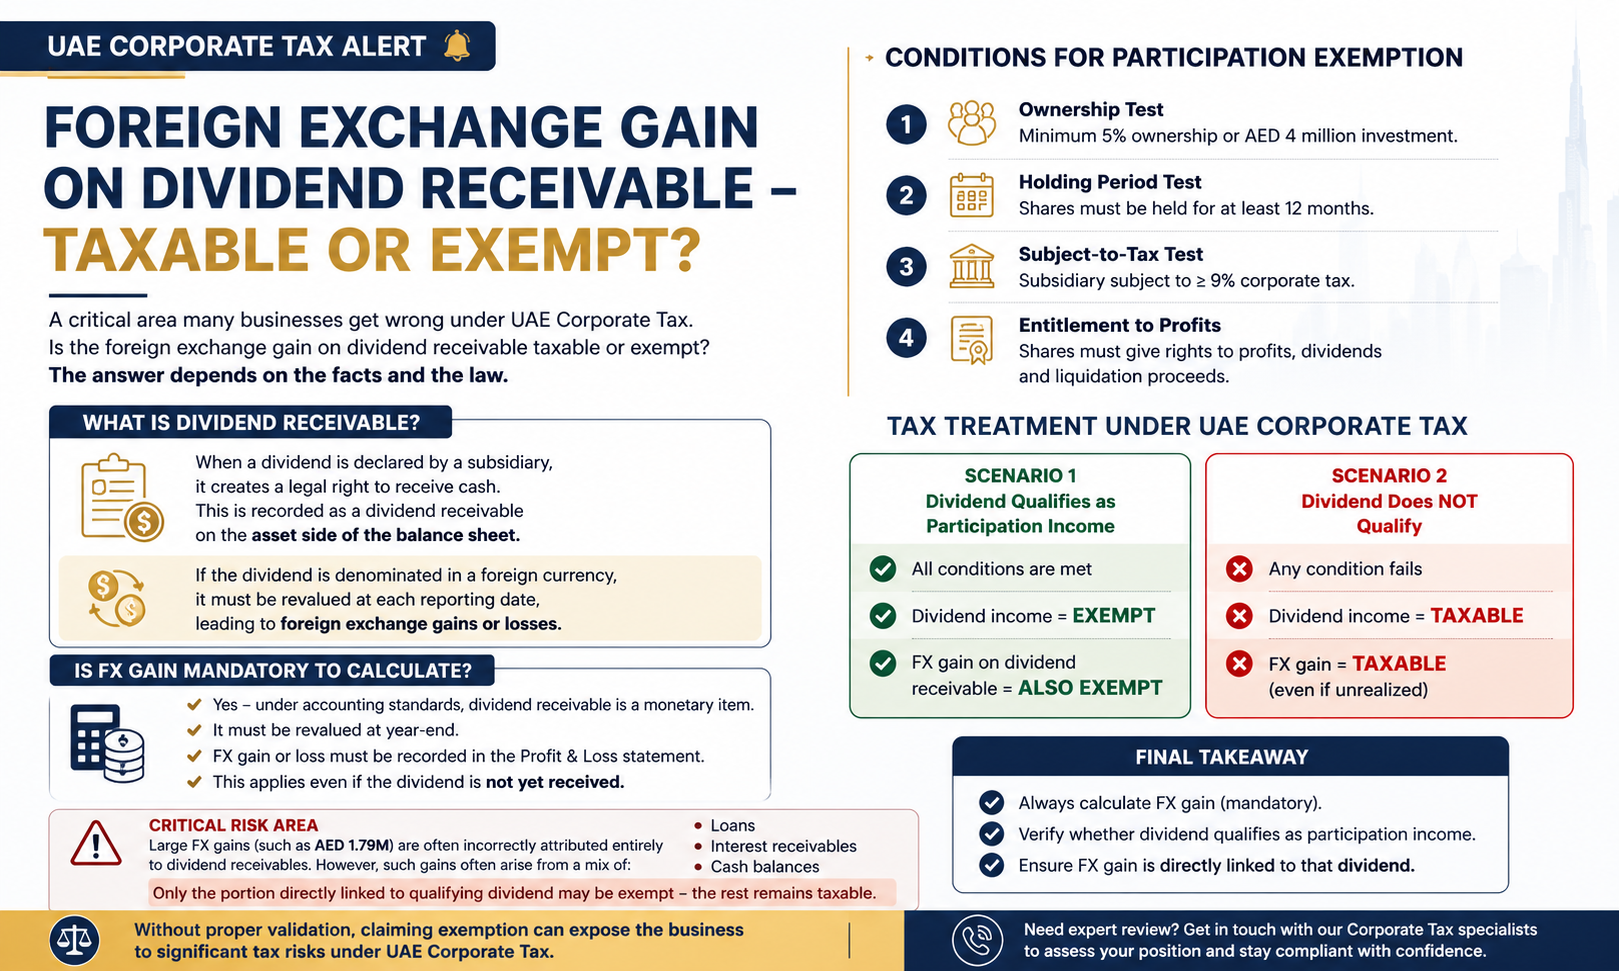
One of the most misunderstood areas under UAE Corporate Tax is the treatment of foreign exchange (FX) gains arising on dividend receivable. Many businesses assume that if the dividend is exempt, the FX gain will automatically be exempt — but this is not always true.
Understanding Dividend Receivable
When a dividend is declared by a subsidiary, it creates a legal right to receive cash. This is recorded as a dividend receivable on the asset side of the balance sheet.
If the dividend is denominated in a foreign currency, it must be revalued at each reporting date, leading to foreign exchange gains or losses.
Is FX Gain Mandatory to Calculate?
Yes — under accounting standards, dividend receivable is a monetary item. This means:
- It must be revalued at year-end
- FX gain or loss must be recorded in the Profit & Loss statement
- This applies even if the dividend is not yet received
Tax Treatment Under UAE Corporate Tax
Here is where it gets critical. The tax treatment of FX gain depends on whether the underlying dividend qualifies as participating income.
Scenario 1: Dividend Qualifies as Participation Income
If all conditions are met:
- Minimum 5% ownership or AED 4 million investment
- 12-month holding period
- Subsidiary subject to ≥9% corporate tax
Then:
- Dividend income = Exempt
- FX gain on dividend receivable = Also Exempt
Scenario 2: Dividend Does NOT Qualify
If any condition fails:
- Dividend income = Taxable
- FX gain = Taxable (even if unrealized)
Common Mistake Businesses Make
Many companies assume:
- “FX gain is unrealized, so not taxable” ❌
- “It relates to dividend, so automatically exempt” ❌
The correct position is:
FX gain follows the tax treatment of the underlying income — not assumptions.
Critical Risk Area
In many cases, large FX gains (such as AED 1.79M) are incorrectly attributed entirely to dividend receivables. However, such gains often arise from a mix of:
- Loans
- Interest receivables
- Cash balances
Only the portion directly linked to qualifying dividend may be exempt — the rest remains taxable.
Final Takeaway
To correctly determine the tax position:
- Always calculate FX gain (mandatory)
- Verify whether dividend qualifies as participation income
- Ensure FX gain is directly linked to that dividend
Without proper validation, claiming exemption can expose the business to significant tax risks under UAE Corporate Tax.
Need Expert Review?
If your company has significant foreign exchange gains or dividend receivables, it is essential to assess eligibility correctly to avoid overpaying or underreporting tax.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0









Comments (0)